Article
How To Use Your Home As Security For A Business Loan Safely
Using your home as security for a business loan can be powerful but dangerous. This guide explains when it’s sensible, when it’s reckless, and how to structure things so one bad year in business doesn’t cost you the family home.
Key Takeaway
Using your home as security for a business loan is safest when total LVR stays under about 70–75%, loans are split clearly by purpose, and business facilities remain in the business’s name with capped director guarantees. This reduces cross‑collateralisation risk that can otherwise trigger forced sale of the family home if the business fails. Small business owners should review current security, guarantees and all‑monies clauses, then restructure into cleaner, stand‑alone facilities before taking on new debt.
Using your home as security for a business loan can be powerful and dangerous at the same time. You generally get lower interest rates and higher limits, but you also put your biggest asset on the line for business risk. The difference between “sensible leverage” and “I’ve put my house on the table at the casino” is almost entirely about structure.
In this guide we’ll unpack when using your home as security can be relatively safe, when it becomes outright dangerous, and the practical changes you can make this week to reduce risk without starving your business of funding.
1. The core idea: what does it really mean to use your home as security?
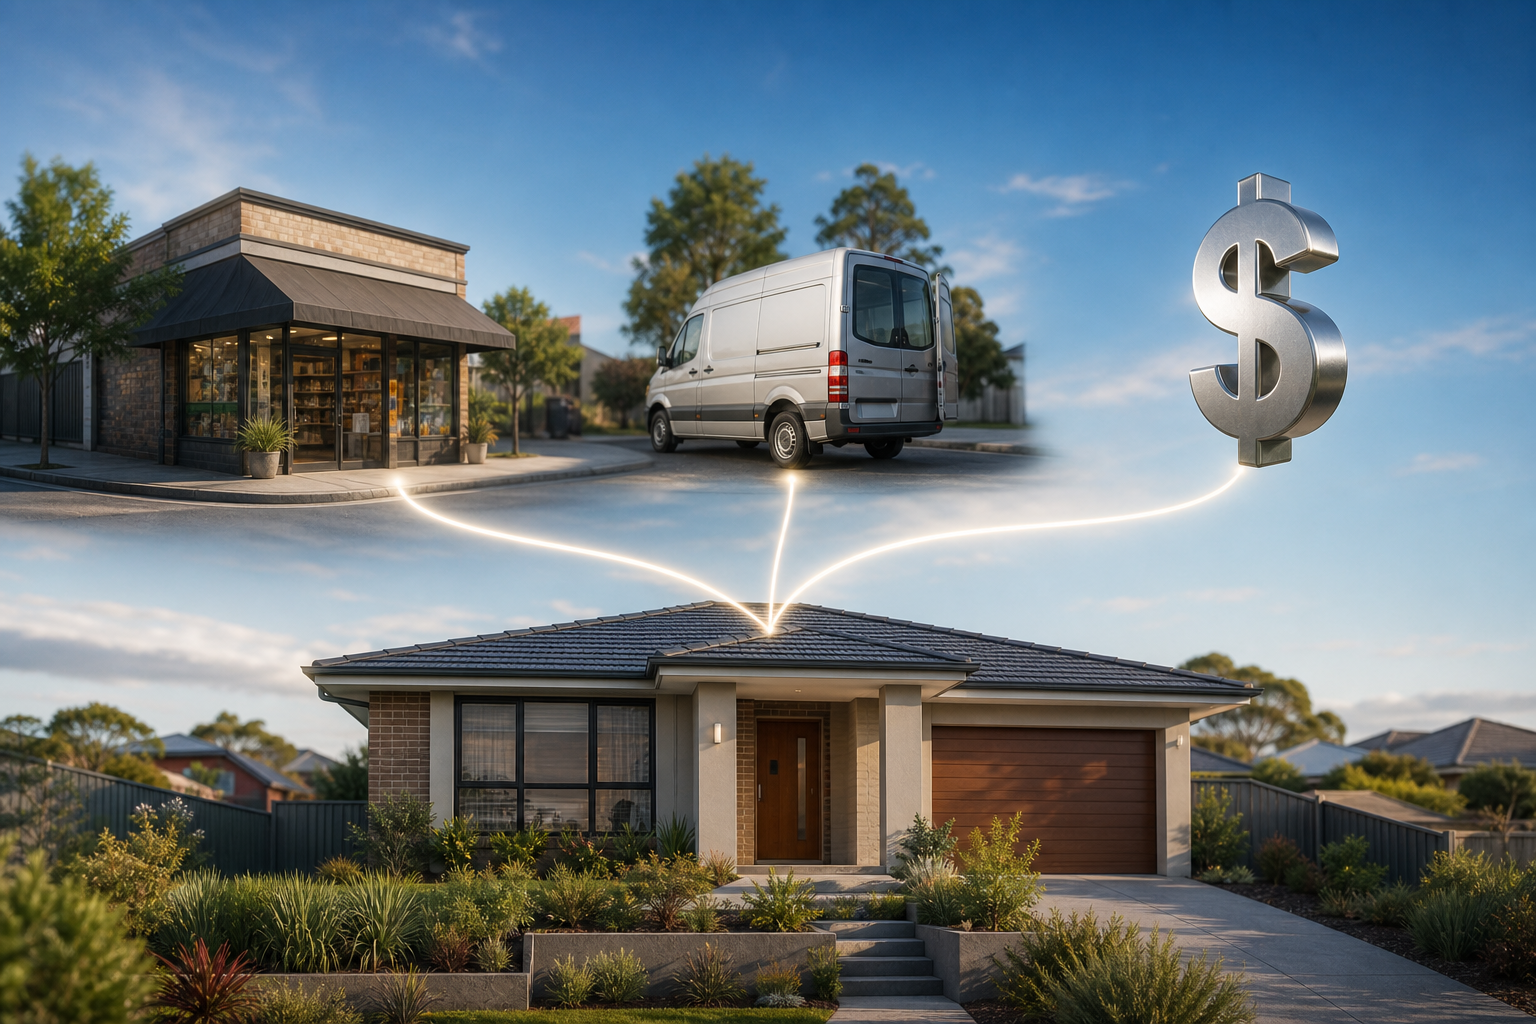
Using your home as security for a business loan means a lender takes a registered mortgage or caveat over your residential property to back a facility that’s used for business purposes.
That can show up as:
- A top‑up or new split on your home loan labelled “business use”
- A separate business facility (overdraft, term loan, equipment finance) with a mortgage over your home
- A second mortgage or caveat from a different lender sitting behind your main home loan
- A director guarantee that effectively drags your home in as security if things go wrong
Under Australian law, once your home is genuinely on the line, the lender can usually force sale of the property if the secured business debt isn’t repaid.
Two important points:
- Form doesn’t matter as much as effect. Even if the business loan is in a company or trust name, your personal assets can be exposed via guarantees and security documents.
- This is cross‑collateralisation. You’re tying business risk to the family home. As we’ve covered in our broader cross‑collateralisation work, that concentrates risk in ways many owners don’t see until it’s too late.
For more on how your home can quietly become the real security for business debt, see /insights/director-guarantees-family-home-risk-business-loans.
2. Why business owners reach for home security (and why banks like it)
Before judging whether it’s safe or dangerous, it helps to understand why this structure is so common.
2.1 The business owner’s perspective
Owners typically offer the home because they:
- Want a lower rate. Property‑secured business loans often price closer to home loan rates than unsecured business lending.
- Need a higher limit. Equity in the home can support larger facilities than cashflow alone would justify.
- Feel time‑poor. Topping up the home loan feels faster and simpler than hunting for dedicated business finance.
- Trust themselves. “I’m not going to fail, so what’s the risk?”
2.2 The lender’s perspective
Banks and non‑banks like home‑secured deals because:
- Residential property is stable, easy to value, and easy to enforce.
- APRA capital rules often treat home‑secured loans more favourably.
- A mortgage over the home plus a director guarantee gives two powerful levers if things get messy.
Post‑COVID, the RBA has noted that credit margins have narrowed and competition has increased, especially in mortgage lending. One side‑effect is that lenders are often happy to “stretch” for business borrowers if they get strong security – which often means the home.
The outcome: the path of least resistance is often “just put it on the house”. That’s not automatically wrong – but it is rarely properly stress‑tested.
3. The big trade‑off: cheaper money vs concentration risk
When you use the home for business, you’re trading price and access for risk concentration.
3.1 Comparing typical options (illustrative only)
Indicative examples only – every lender and borrower is different:
| Facility type | Typical security | Approx. max term | Indicative rate range* | Usual purpose |
|---|---|---|---|---|
| Home loan split for business use | Main residence | 25–30 years | Near home loan rates | General business, working capital |
| Property‑secured business term loan | Home or commercial prop | 5–15 years | +1–3% over home loan | Fit‑out, goodwill, expansion |
| Unsecured / semi‑secured business loan | Director guarantee only | 1–7 years | Higher business rates | Short‑term working capital, marketing |
| Equipment finance (chattel mortgage) | The asset itself | 3–7 years | Mid‑range business | Vehicles, machinery, equipment |
*Rates are indicative only and change regularly. Always check current offers.
The rate saving by using home equity might be 1–4 percentage points compared with unsecured business finance. That looks attractive. But you’re also:
- Extending short‑life costs over up to 30 years
- Putting the home in the firing line
- Making it harder to move lenders or restructure later
Our existing work on when not to roll business debt into the home goes deep on this trade‑off – see /insights/consolidate-business-loans-into-home-mortgage.
3.2 Concentration risk in today’s mortgage‑stress environment
Roy Morgan’s July 2026 data shows around 32.5% of Australian owner‑occupier mortgage holders are ‘At Risk’ of mortgage stress, with 22% ‘Extremely At Risk’. At the same time, many small businesses are dealing with higher rates, softer demand and rising wages.
If you:
- Already have a stretched home loan; and
- Then add business risk onto the same property
…you’re stacking two volatile factors on top of each other. One bad patch in business, plus another RBA hike, and suddenly the family home is in play.
4. When using your home can be relatively safe
It’s rarely perfectly safe – but there are structures that keep risk within sensible bounds.
4.1 Core features of a “safer” structure
A relatively safe approach usually looks like this:
-
Conservative LVR:
- Total lending against the home ≤ 70–75% LVR (loan‑to‑value ratio).
- This buffer helps absorb valuation drops and lender margin calls.
-
Clear loan splits by purpose:
- A home loan split for the PPR (principal place of residence) only.
- Separate, clearly labelled splits for business equity release.
- Each split has its own repayment schedule and limit.
-
Matched loan terms:
- Fit‑out or working capital drawn from home equity is on short, 3–7 year terms, not 25–30 years.
- This keeps interest cost down over the life of the business expense.
-
Business debt mostly in business facilities:
- Core working capital, overdrafts and equipment are in dedicated business facilities, not sitting in your home loan offset.
- This preserves tax clarity and avoids turning the mortgage into an informal overdraft.
-
Limited guarantees and clean documents:
- Director guarantees are capped and specific, not “all‑monies” across everything.
- All‑monies and broad indemnity clauses are reviewed and, where possible, narrowed.
We unpack practical ways to design this in /insights/designing-asset-protection-around-your-home-trusts-guarantees-exits.
4.2 Worked example: modest, time‑boxed equity release
- Home value: $1,600,000
- Existing home loan: $800,000 (50% LVR)
- Business need: $150,000 for a clinic fit‑out
Safer structure:
- Add a new split on the home loan: $150,000
- Total loans on home: $950,000 → ~59% LVR
- New split set as 5‑year P&I, clearly labelled “Business clinic fit‑out”
- Remaining business needs handled via a small overdraft and equipment finance
Why this is relatively safe:
- LVR still under 60% – plenty of buffer
- Business cost is scheduled to be repaid over 5 years, consistent with fit‑out life
- You don’t use the offset as a revolving working capital bucket
Compare that to a riskier version:
- Same $150,000 added to the main 30‑year home loan
- Interest‑only for 5 years, then 25‑year principal term
- Purpose not clearly documented
Here, you’re far more likely to still be paying for that fit‑out decades after it’s been ripped out by the next tenant.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 9 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Is it ever safe to use my home as security for a business loan?▾
What is a safe LVR if my home secures business debt?▾
Are second mortgages or caveats safer than topping up my main home loan?▾
How do director guarantees put my home at risk if there’s no mortgage on it?▾
Should I roll expensive business loans into my home mortgage to save interest?▾
Does using my home as security affect tax deductibility of interest?▾
Can I separate my home and business loans without losing borrowing power?▾
Request a strategy call
Confidential consultation with a triple-qualified advisor — commercial, SMSF, equipment and development finance.