Article
How To Design Real Asset Protection Around Your Home In Practice
Your home is usually your biggest asset and your biggest target. This guide shows Australians how to design real-world asset protection around the family home using trusts, guarantees and clear exit strategies — without destroying borrowing power or tax outcomes.
Key Takeaway
Designing asset protection around a home in Australia starts with controlling how loans, guarantees and ownership structures expose the family home, not just putting it in a trust. Because interest deductibility follows loan purpose, not security, trust or cross-collateral structures rarely add tax benefits but can add risk if misused. Effective protection means limiting director guarantees, avoiding unnecessary cross‑collateralisation, and pre‑planning exit strategies—such as sale thresholds and refinance plans—so borrowers can act quickly if business or cash flow deteriorates.
Most people think asset protection for the family home means “put it in a trust and you’re safe”. In practice, the real danger usually comes from something far more boring: loan documents, guarantees and the lack of a clear exit plan when things go sideways. I see more homes lost to sloppy security and guarantees than to not having a trust at all.
In Australia, designing asset protection around your home means controlling three things: (1) who owns the home, (2) what actually secures which loans, and (3) how you’ll unwind things fast if income falls or the business hits trouble. Structure is important, but the paperwork and the plan matter just as much.
1. The real goal: keep one asset “safest in the room”
What I tell my clients
The mistake I see most is trying to protect everything equally. You end up over‑structuring, confusing lenders and still signing guarantees that quietly drag the home back into the firing line.
What I tell my clients is simple: pick one asset to be the safest in the room. For most Australians, that’s the family home.
That means:
- Owning it in a way that supports lending and tax (often in personal names).
- Minimising when it’s offered as security for business or investment risk.
- Having a written exit strategy where protecting the home beats saving every investment or venture.
You’ll see this theme through my other guides on keeping business and home debt separate (/insights/keeping-business-and-home-debt-legally-separate-without-hurting-borrowing-power) and protecting your home while using equity for investments (/insights/structuring-investment-loans-when-wealth-in-family-home).
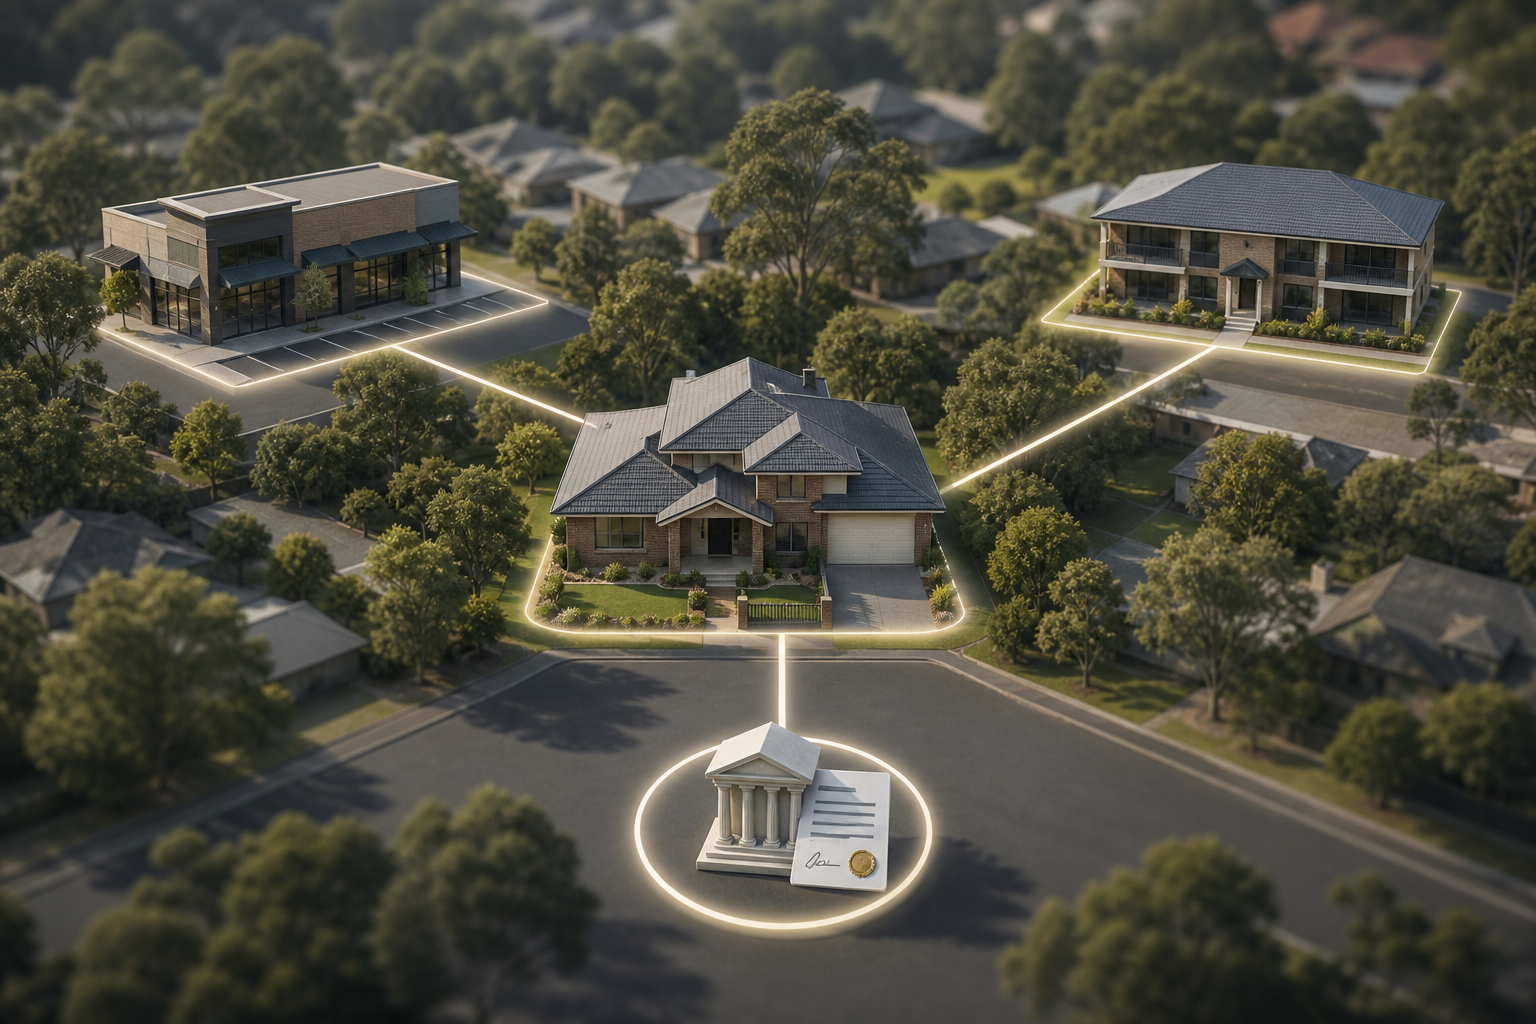
2. Trust vs no trust: asset protection is in the details
When a trust around the home actually helps
Putting the home in a discretionary trust can improve asset protection in some cases: high‑risk professionals, directors with big personal exposure, or families where one partner runs a trading business.
If the trust is properly drafted and controlled by the “safer” spouse, and if personal guarantees are tightly managed, creditors chasing the risky spouse often face a higher hurdle to reach the home.
But there are clear trade‑offs:
- You usually lose full main residence CGT exemption and land tax concessions (often a six‑figure long‑run cost on higher value properties – see /insights/discretionary-trust-own-family-home-asset-protection-tax).
- Lending is harder: fewer lenders, lower max LVRs, and more scrutiny of the trust deed (/insights/how-lenders-assess-home-loans-family-trust).
- You almost always still sign personal and director guarantees.
So a trust can be part of your asset protection toolkit, but it’s not a forcefield.
Asset protection without a trust
For many households, the smarter move is:
- Own the family home in personal names (often split between spouses according to risk profile).
- Keep business risk quarantined in a company or trust.
- Be extremely careful about when and how the home is used as security for business or investment loans.
A key principle from my broader work: interest deductibility depends on loan purpose, not which property secures the loan. So putting the home in a company or trust does not magically make home loan interest deductible (see /insights/lending-reality-buying-home-through-entity-2 and /insights/guarantor-family-pledge-loans-self-employed).
From a tax and lending angle, you often get:
- Better rates and policies in personal names.
- Simpler refinancing later.
- Clearer separation between home and business if you don’t casually pledge the home.
3. Guarantees: the quiet way your home becomes business security
How director guarantees really work
You might think “the company is borrowing; my home is safe”. Then you sign a standard director’s guarantee and an all‑monies mortgage, and suddenly the “business” facility is economically secured by your house.
The key risks I see, and unpack more fully in /insights/director-guarantees-family-home-risk-business-loans:
- All‑monies clauses – your home can be on the hook for any present or future facility with that lender.
- Cross‑collateralisation – one default can trigger a clean‑out across home, business and investment properties.
- Caveats over the home – from trade creditors or alt‑doc lenders tied to personal guarantees.
Roy Morgan has mortgage stress at record levels, with over 30% of borrowers “At Risk”. Layering poorly‑managed guarantees on top of that is how a business wobble turns into a family housing crisis.
A simple guarantee control framework
Here’s how I like clients to manage guarantees around the home:
- Guarantee register – maintain a written list of every personal and director guarantee, linked to the loan and any security. (This is step one in /insights/checklist-review-personal-guarantees-broker-accountant-lawyer.)
- No surprises rule – do not sign guarantees at a branch or on Zoom without your broker, accountant and lawyer having seen the actual documents first.
- Limit and ring‑fence – wherever possible:
- Cap the guarantee amount.
- Exclude the family home from supporting business facilities, or at least avoid all‑monies wording.
- Use stand‑alone business security (plant, equipment, debtors) where the economics stack up.
- Exit dates and triggers – for each business facility, identify when you expect to refinance, reduce or exit the loan, and what business metrics must hold (EBITDA, cashflow coverage) to justify keeping the guarantee.
This is all boring admin work – until you need it. Then it’s the difference between negotiating from a position of strength or watching the home disappear.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 6 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Does putting my home in a trust completely protect it from creditors?▾
If my company borrows, can the bank still take my house?▾
Is cross‑collateralisation always bad for asset protection?▾
Can I fix my structure if loans and guarantees are already messy?▾
How often should I review my asset protection plan?▾
Request a strategy call
Confidential consultation with a triple-qualified advisor — commercial, SMSF, equipment and development finance.