
Article
How to Use a Business Offset Account To Tame Lumpy Income
A practical guide for self‑employed pros, contractors and small practices on using a business offset-style setup to smooth lumpy income, ring‑fence tax and keep lenders comfortable.
Key Takeaway
Using a business offset-style account structure helps self‑employed Australians smooth lumpy professional income by separating trading cash, tax money, and household spending while preserving interest savings on home or business debt. A simple three‑ or four‑account setup with a fixed “wage” transfer pattern can materially improve lender views of income stability and reduce ATO shock risk. The key action is to implement automatic splits of every deposit into trading, tax, and personal buckets within the next month.
Watch the short answer
How ABN age can affect your chances with the banks
While you’re working out how to smooth lumpy income, this video explains how your ABN age can shape what banks are willing to lend.
Read the transcript
Most banks have a rigid rule: if your ABN hasn't been active for two full years, you can't get a home loan. But if your trade business has been booming for 12 months, why should your family wait to buy a house? We have direct access to alternative doc lenders who accept 6 to 12 months of active trading backed by clean business bank deposits. Stop waiting for arbitrary timelines. DM me 'GROWTH' to look at your options.
General information only, not personal advice. Your situation is assessed before any recommendation.
Self‑employed income is rarely neat. One month you’re drowning in invoices paid early, the next you’re watching the ATO deadline creep closer while three big clients drag their feet.
A business offset account (or an offset‑style cash structure) is a way to park surplus business cash against debt while still keeping tax money ring‑fenced and your drawings smooth. Done properly, it reduces interest, calms cashflow, and makes your bank statements look a lot more like a stable PAYG salary.
This guide walks through how to set that up without confusing the taxman or spooking future home‑loan lenders.
1. What do we actually mean by a “business offset account”?
Banks don’t always use the term the same way, and not every lender offers a true offset on business loans.
For this guide, think of a business offset account as one of two things:
-
True offset against a business loan
A transaction account formally linked to a business loan or commercial facility where every dollar in the account reduces the interest calculated on that loan. -
Offset‑style cash hub
A high‑interest business transaction or saver account that sits beside your loans and holds surplus trading cash, not tax money or household spending. It’s not legally an offset, but functionally it behaves like a buffer that reduces your overall interest bill and keeps working capital in one place.
Most small practices, sole traders and contractors will use option 2, because:
- True business offsets are less common and sometimes come with higher margins or package fees.
- You often get close to the same outcome by parking surplus cash in a high‑interest business account while your home loan offset does the heavy lifting for the household.
The key principle: you want a structure that lets you keep three things clearly separated:
- Business operations
- Tax and GST
- Personal and home‑loan life
If those lines blur, the ATO and future lenders start getting nervous.
2. Why lumpy professional income needs a different cash structure
Self‑employed professionals, locums, contractors and partners in practices all share the same basic problem: income lands in big, irregular chunks.
Common patterns:
- Quarterly billers (legal, consulting, engineering, advisory): months of work, one chunky invoice.
- Locums and sessional doctors/allied health: swings in sessions and last‑minute roster changes.
- Project‑based consultants and creatives: milestone payments, success fees and retainers that pause.
- Professional partnerships: drawings linked to firm performance, not neat fortnightly salaries.
If you run everything through one or two accounts, three bad things usually happen:
-
Tax money gets spent
BAS, GST and PAYG become accidental working capital. When the ATO bill lands, you’re scrambling. (See the detailed approach in /insights/bas-gst-payg-structuring-accounts-tax-working-capital.) -
Home‑loan borrowing power suffers
Lenders see lumpy drawings, mixed business and personal spending, and transfers flying every which way. It’s harder to prove stable income. /insights/separate-business-personal-cashflow-lenders-see-real-story shows how much this matters. -
You use the wrong buffers
It’s tempting to dip into home‑loan redraw or personal offsets to plug business gaps. That concentrates business risk on the family home and tangles tax deductibility.
A business offset‑style setup fixes this by:
- Forcing you to skim tax and GST from every receipt.
- Letting you pay yourself a fixed “wage” even when revenue jumps around.
- Keeping ATO money and working capital away from the home loan, while still giving you interest savings.
3. Core structure: how many accounts do you actually need?
You don’t need eight accounts and a spreadsheet PhD. For most professionals, it comes down to three or four accounts, plus an optional offset link.
3.1 The three‑account minimum (sole traders and simple ABNs)
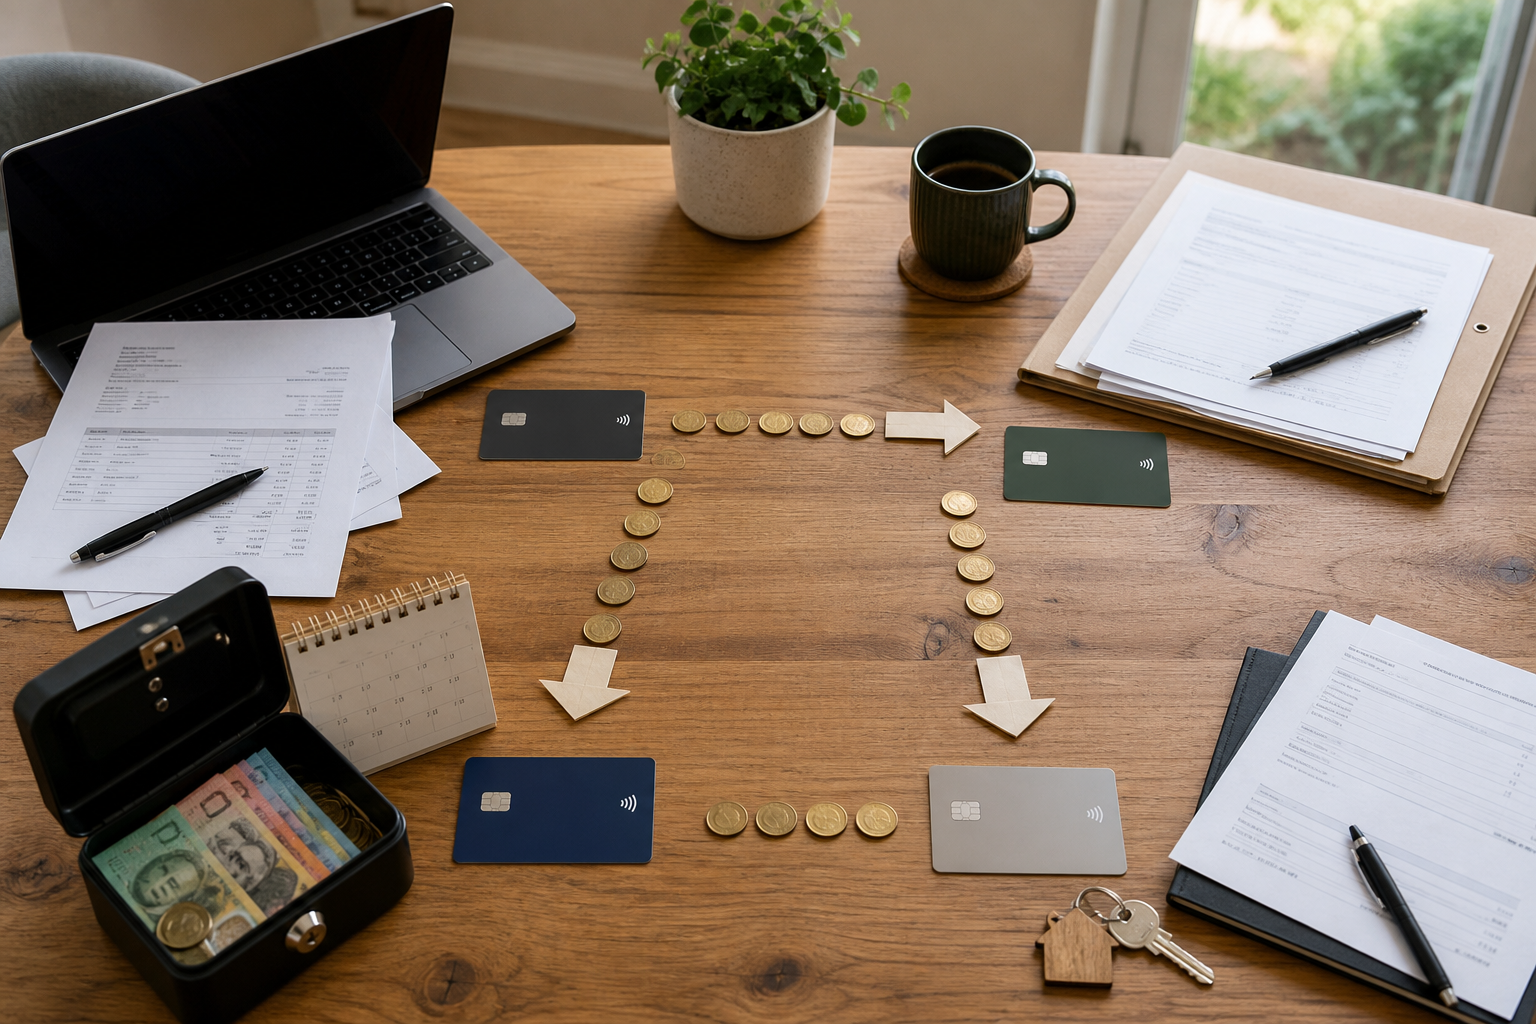
If you work under your own name or a simple ABN, a three‑account setup will usually do the job:
-
Business trading account
- All client invoices are paid in here.
- All business expenses (rent, software, insurances, contractors) are paid from here.
- This is the account you reconcile in Xero or MYOB.
-
Business tax/GST holding account
- A fixed percentage of every dollar that hits the trading account is swept here (e.g. 25–35% depending on your GST status and marginal tax rate).
- You do not touch this except to pay BAS, GST, PAYG and income tax.
-
Personal everyday/offset‑linked account
- You pay yourself a fixed weekly or fortnightly “wage” from the trading account into this account.
- This is where groceries, school fees, utilities, and personal spending live.
- Ideally this is either your main home‑loan offset or is linked closely to it.
This basic shape is unpacked in /insights/best-offset-account-setups-sole-traders-working-from-home. It turns lumpy business income into something lenders recognise: regular, PAYG‑style cashflow.
3.2 The four‑account structure (companies, partnerships and bigger practices)
If you trade via a company, trust or partnership, add one more account:
- Business offset / surplus working‑capital account
- A transaction or saver account used as the buffer for business cash, not personal spending.
- Holds surplus beyond what’s needed for the next 30–60 days of bills and payroll.
- Ideally earns interest or offsets a business facility.
The roles then look like this:
- Trading account: day‑to‑day in and out.
- Tax account: ATO only.
- Business offset / buffer: lumpy surplus; source of stable drawings.
- Personal everyday/offset: household life and home‑loan saving.
Run this cleanly for 3–6 months, and most lenders become far more comfortable that the drawings you take are sustainable.
4. How the flows work: from lumpy invoices to smooth drawings
Let’s make it concrete with a worked example.
4.1 Worked example – consultant with quarterly invoices
Assumptions:
- You’re a consultant invoicing quarterly.
- Average annual revenue: $360,000 + GST (so $90,000 + GST per quarter).
- You’re registered for GST and on a 32.5% marginal tax rate.
- You want to pay yourself $7,000 per fortnight as a personal “wage”.
Step 1 – Invoice is paid
- $99,000 (incl. GST) lands in the Business trading account.
Step 2 – Auto‑split the money
You set up two automatic transfers on every significant deposit:
-
GST and tax skim
- GST portion: $9,000
- Income tax/ATO buffer: say 25% of the ex‑GST amount (25% × $90,000 = $22,500).
- Total transfer to Tax/GST account: $31,500.
-
Working‑capital sweep
- You decide the trading account only needs $25,000 to cover the next 30–45 days of expenses.
- Surplus ($99,000 − $31,500 − $25,000 = $42,500) is moved into the Business offset/buffer account.
Step 3 – Pay yourself a stable “wage”
- You transfer $7,000 per fortnight from the Business trading account to your Personal everyday/offset account.
- Over the 13‑week quarter that’s $45,500 (a bit above your surplus, so the trading account will draw on the buffer at some point).
Effect over the quarter
- When cash is high (right after invoices land), the trading account tops up.
- When cash is low (towards the end of the quarter), the Business offset/buffer quietly feeds the trading account to keep your “wage” stable.
From a bank’s perspective:
- Your personal account shows regular, predictable income.
- Your business accounts clearly show:
- Revenue
- Clean business expenses
- Tax ring‑fenced
- No messy transfers with the home loan.
That is exactly the story you want visible before any home‑loan or refinance application.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 9 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Can I link a business offset account directly to my home loan?▾
How big should my business cash buffer be in an offset-style account?▾
Do I still need an overdraft if I have a healthy business offset balance?▾
How does a business offset-style structure help with home loan applications?▾
What if my bank doesn’t offer a true business loan offset account?▾
How long should I run this account structure before refinancing or buying a home?▾
Request a strategy call
Confidential consultation with a triple-qualified advisor — commercial, SMSF, equipment and development finance.