
Article
Structure Your Cashflow So Lenders See the Real Business Story
A practical guide to separating business and personal cashflow so lenders see clean income, not chaos. Set up bank-friendly accounts, fix red flags, and protect your borrowing power this year.
Key Takeaway
This guide explains how to separate business and personal cashflow so Australian lenders see clear, stable income instead of messy statements that weaken borrowing capacity. Because banks assess visible cashflow and tax conduct rather than “true profit”, setting up 3–4 clean accounts, paying a fixed wage, and ring‑fencing tax for at least six months can materially improve approval odds. Readers get step‑by‑step structures and timelines they can implement this week to protect both business resilience and home loan potential.
Watch the short answer
How ABN age can affect your chances with the banks
While you’re sorting your cashflow story for lenders, this video explains how your ABN age can change what the banks will consider.
Read the transcript
Most banks have a rigid rule: if your ABN hasn't been active for two full years, you can't get a home loan. But if your trade business has been booming for 12 months, why should your family wait to buy a house? We have direct access to alternative doc lenders who accept 6 to 12 months of active trading backed by clean business bank deposits. Stop waiting for arbitrary timelines. DM me 'GROWTH' to look at your options.
General information only, not personal advice. Your situation is assessed before any recommendation.
Busy, self‑employed people often tell me, “The business is doing well, but the bank just can’t see it.”
For lenders, separating business and personal cashflow is the difference between “too messy, too risky” and “strong, stable borrower”. They don’t lend against what you really make; they lend against what they can clearly see in your bank statements, BAS and tax returns. This guide shows how to set up bank‑friendly cashflow so lenders see the real story — and what you can change this week.
In plain English: Keep business income and expenses in business accounts, keep personal spending and savings in personal accounts, pay yourself a consistent wage or drawings, and avoid using home loan redraw or personal offset as a business overdraft. Do this for at least 3–6 months before a home loan and your borrowing power usually improves.
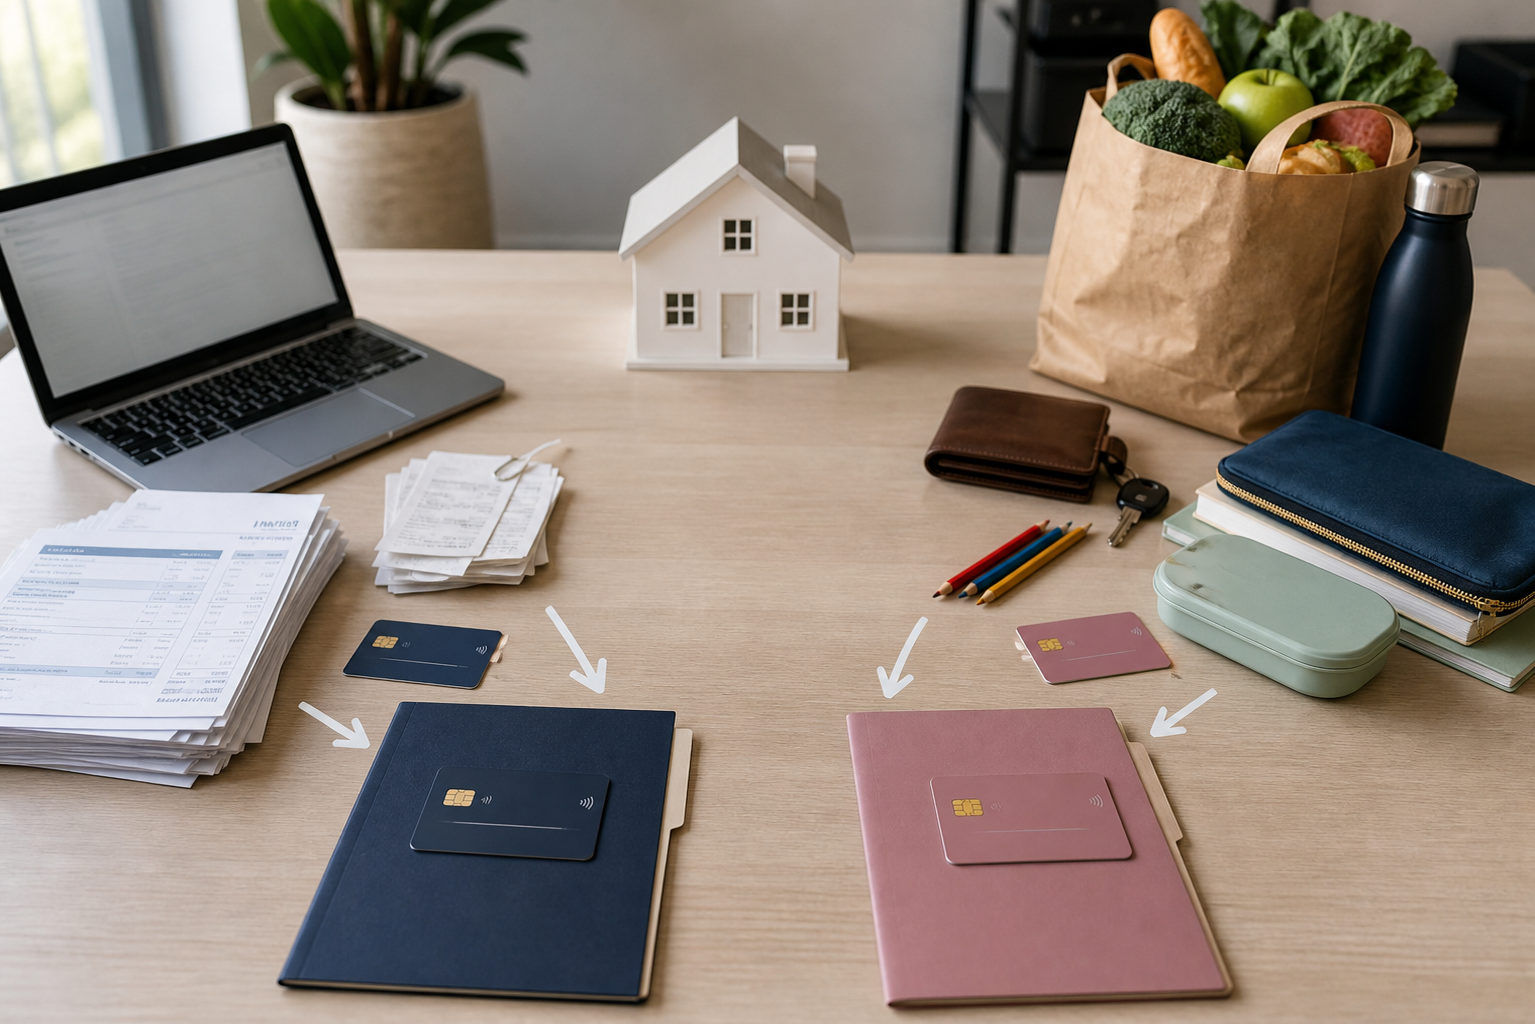
1. Why clean separation matters so much to lenders
1.1 What banks actually look at
When you apply for a home or investment loan as a business owner, lenders typically review:
- 6–12 months of personal bank statements
- 6–12 months of business trading account statements
- 2 years’ tax returns and notices of assessment
- BAS, GST and PAYG accounts if you’re self‑employed
- Any business loan and overdraft statements
From that, they’re trying to answer three questions:
- Is income stable and predictable? Or does it spike and crash?
- Is tax under control? Or are ATO debts building up?
- Is personal spending reasonable? Or are there hidden commitments?
Mixed accounts make all three questions harder to answer. When lenders can’t untangle the story, they default to conservative assumptions — and your borrowing power drops.
1.2 How mixed cashflow kills borrowing power
Mixed business–personal accounts create problems like:
- “Phantom” living expenses – personal spending from the business account gets counted on top of your drawings or salary.
- Hidden business costs – suppliers paid from personal accounts look like extra living costs, not business expenses.
- ATO risk signals – using GST or PAYG as a buffer screams “under‑funded working capital” to credit teams.
- Redraw as overdraft – repeatedly dipping into home loan redraw or personal offset to cover wages, stock or BAS is treated as a sign of weak cashflow and poor structuring (see facts 1, 2, 5–7, 13, 19–20 in the hub).
All of this makes it harder to argue for income add‑backs and exceptions. By contrast, clear separation makes lenders more willing to believe the numbers and accept adjustments.
If you want a deeper dive on how banks read your accounts, see: Make Your Business Bank Accounts Work For Your Home Loan.
2. The bank‑friendly cashflow setups that actually work
2.1 For sole traders and contractors
For most home‑based sole traders, the simplest effective structure is three accounts (knowledge fact 11):
- Business trading account – all business income in, all business expenses out.
- Tax/GST holding account – regular transfers for GST, PAYG and income tax.
- Personal everyday account – used for household spending and linked to your home loan offset.
This mirrors the setup in Offset account setups that actually work for sole traders.
How it works in practice:
- All invoices are paid into the business trading account.
- You move GST and tax weekly or fortnightly into the tax/GST account.
- You pay yourself a fixed weekly or fortnightly “wage” from the trading account to your personal account (knowledge fact 10). Lenders love this.
2.2 For small companies and family trusts
For most small Australian companies, a four‑account structure is usually enough (knowledge fact 3):
- Company trading account
- Company tax/GST account
- Household everyday account
- Home loan offset account
You might add a fifth for retained profits / rainy day reserves, but it’s not essential for lending clarity.
Then:
- Wages or director fees are paid from the trading account to your personal account through payroll.
- Dividends are paid in clean, occasional lump sums and clearly labelled.
- No personal spending occurs from the company accounts.
For more complex group structures, see: Set Up Company and Trust Cashflow So Your Home Loan Stays Clean.
2.3 Why redraw and offset are bad business overdrafts
Using home loan redraw or personal offset as a revolving business buffer might feel clever, but lenders see it as:
- Under‑funded working capital
- Blurred tax deductibility
- Directly exposing your home to trading risk (facts 1–2, 5–7, 13, 15, 19–20)
It also muddies your personal cashflow story. Regular large transfers from your offset to the business look like extra personal commitments in the eyes of a credit assessor.
If you need a buffer, it’s nearly always cleaner to set up:
- A small business overdraft, or
- A working capital facility sized to real needs.
This is exactly what we cover in the parent topic: Working Capital and Your Home Loan: Protecting Borrowing Power.
3. Business vs personal cashflow: side‑by‑side
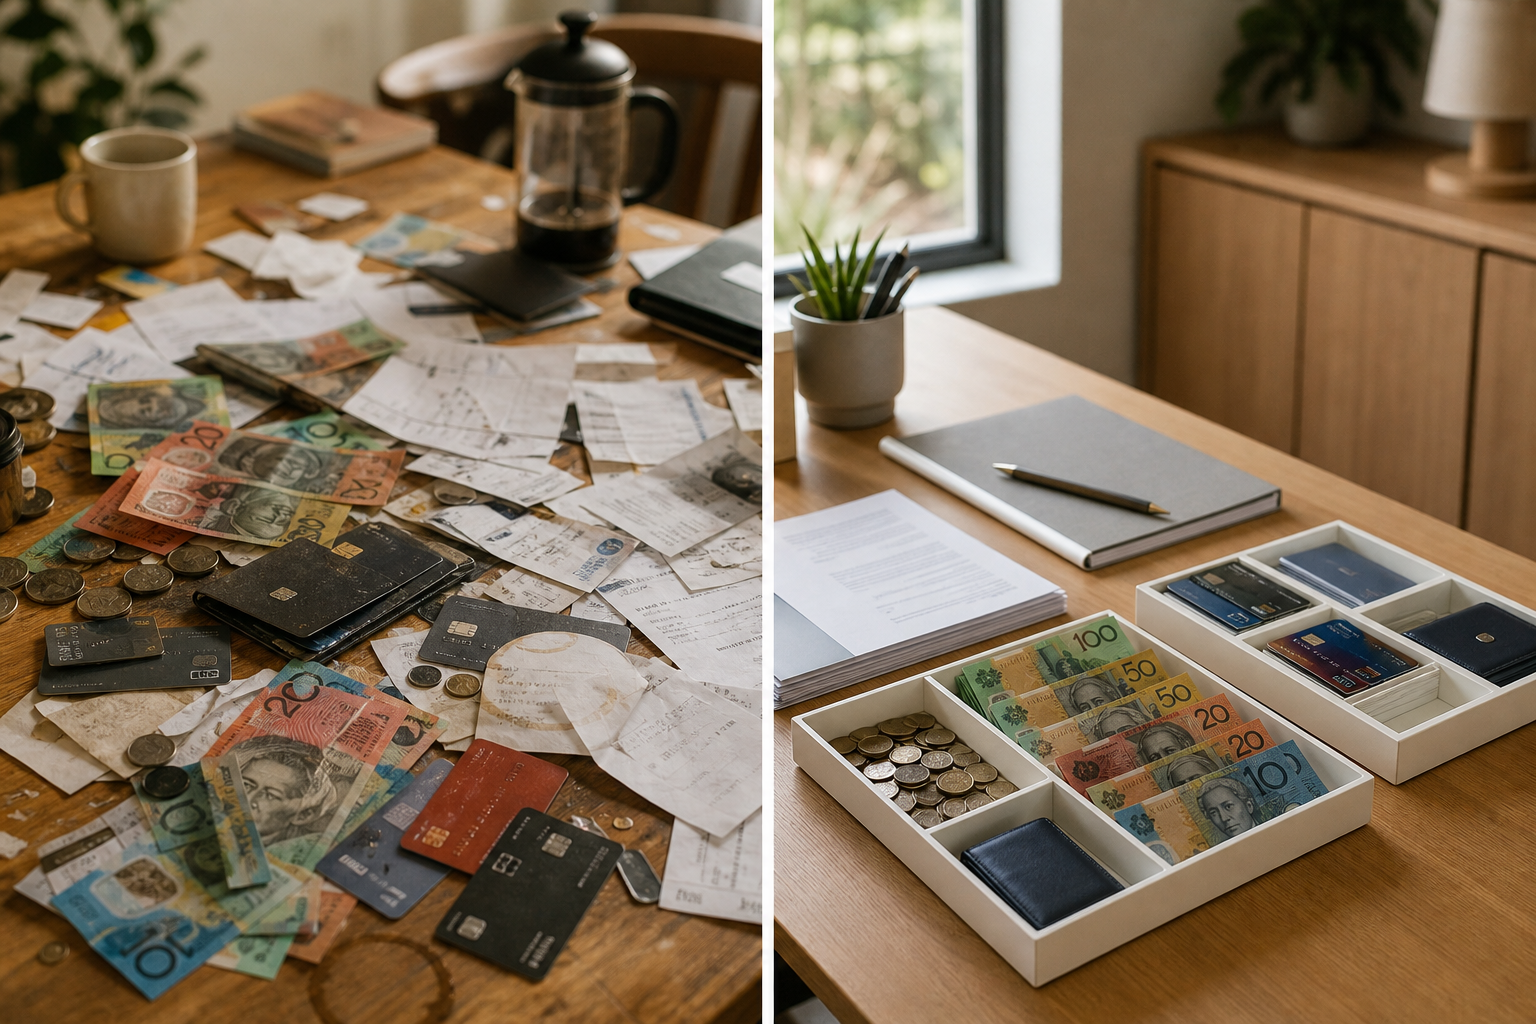
Here’s how mixed vs separated cashflow usually looks to a lender.
| Feature / Behaviour | Mixed Accounts (Risky) | Separated Accounts (Bank‑Friendly) |
|---|---|---|
| Business income | Paid into personal & business accounts randomly | Paid only into business trading account |
| Personal spending | Comes from business and personal accounts | Comes only from personal account |
| Tax & GST | Left in trading account, used as buffer | Moved regularly to dedicated tax/GST account |
| Owner’s pay | Irregular drawings, ad‑hoc transfers | Fixed weekly/fortnightly wage or drawings |
| Use of home loan redraw/offset | Frequent transfers to cover wages, stock, BAS | Rare, only for personal reasons with clear documentation |
| How statements look to a lender | Chaotic, hard to separate business vs living expenses | Simple salary or drawings pattern + normal household spending |
| Likely impact on borrowing power | Conservative income, higher assessed expenses, lower borrowing | Higher usable income, cleaner expenses, better chance of approval |
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 7 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
How long do I need clean separated accounts before applying for a home loan?▾
Do I really need a separate business account if I’m just a small sole trader?▾
Will paying myself a fixed wage hurt my tax position?▾
What if I’ve already been using my home loan redraw to fund the business?▾
Can I fix messy accounts quickly just before I apply?▾
Do lenders look at my ATO position when assessing a home loan?▾
Request a strategy call
Confidential consultation with a triple-qualified advisor — commercial, SMSF, equipment and development finance.