
Article
Refinancing in Bronte When Values Fall: Safe Options With a Tight LVR
If Bronte property values have softened and your LVR is tight, full refinancing may be limited – but you still have options. This guide walks through realistic paths to lower repayments, manage risk and keep future flexibility, even when equity is thin.
Key Takeaway
When Bronte values soften and a borrower’s loan-to-value ratio (LVR) is tight, full refinancing is often restricted because many banks cap standard LVRs around 80% without lenders mortgage insurance (LMI) and 90–95% with it. Owners can still negotiate sharper rates with their current lender, do partial refinances, restructure loan splits, or adjust repayments and buffers to reduce risk. A clear first step is to confirm a realistic valuation and LVR, then choose the safest option that preserves flexibility.
Watch the short answer
How business debt, home loans and tax strategy fit together
If you juggle business and home loans, this shows how they link with your overall tax position.
Read the transcript
Your business debt, your home loan, and your tax strategy are all fighting each other. When self-employed operators use different banks, an accountant, and a generic online broker, their financial web becomes tangled. Your business equipment loan starts blocking your residential refinance. We act as the central architect. We map your entire portfolio, placing your asset finance, commercial loans, and residential debt in strategic isolation so one doesn't drag down the other. Untangle your wealth. DM me the word 'ARCHITECT' for a holistic portfolio review.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Tailored Loans Sydney
If Bronte property values have softened and your LVR is tight, full refinancing may be limited – but you still have options. This guide walks through realistic paths to lower repayments, manage risk and keep future flexibility, even when equity is thin.
Read the full guide on tailoredloans.sydneyIf Bronte values have softened and your LVR is tight, you may not be able to do a clean refinance to a new lender – but you still have options to reduce pressure, lower risk and keep future flexibility.
In a softer Bronte market, the priority is to: 1) confirm your real LVR, 2) work out if refinancing is actually possible, and 3) if not, use every in‑place lever with your current lender before considering bigger moves like selling.
1. First job: know your real LVR in today’s Bronte market
Your loan‑to‑value ratio (LVR) is simply:
LVR = total loans secured ÷ realistic property value × 100
When prices slip, your LVR can jump quickly – especially if you borrowed at 90–95% originally.
A. Get a realistic value, not a headline
In a soft patch, online estimates can be 5–10% off.
Practical steps this week:
- Ask your broker or bank whether they’ll use a desktop or full valuation.
- Cross‑check with two recent, similar Bronte sales – same side of Macpherson, similar land or unit size.
- Sense‑check against where Bronte sits in its cycle using /insights/reading-bronte-property-cycles-flat-rising-hot-actions.
B. Typical LVR limits when values soften
Banks don’t publish this clearly, but in softer Eastern Suburbs markets they tend to:
- Hold 80% as the “clean” refinance LVR without LMI.
- Be much fussier above 80%, often capping refinances around 85–90%.
- Treat some Eastern Suburbs postcodes as higher risk, tightening policy (see /insights/eastern-suburbs-postcode-risk-lists-where-banks-get-cautious).
C. Quick worked example – how a value dip traps a refinance
- 2022: Bronte house bought for $3.0m, loan $2.7m (90% LVR).
- 2026: market softens, realistic value now $2.7m.
- Current loan still ~$2.6m.
New LVR ≈ $2.6m ÷ $2.7m = 96%.
Most lenders won’t refinance this without heavy LMI and very strong income. You’re effectively in a “hold and manage” phase, not a “shop around freely” phase.
2. Your main options when your LVR is tight
You have more levers than just “refinance or do nothing”. The right mix depends on your LVR band.
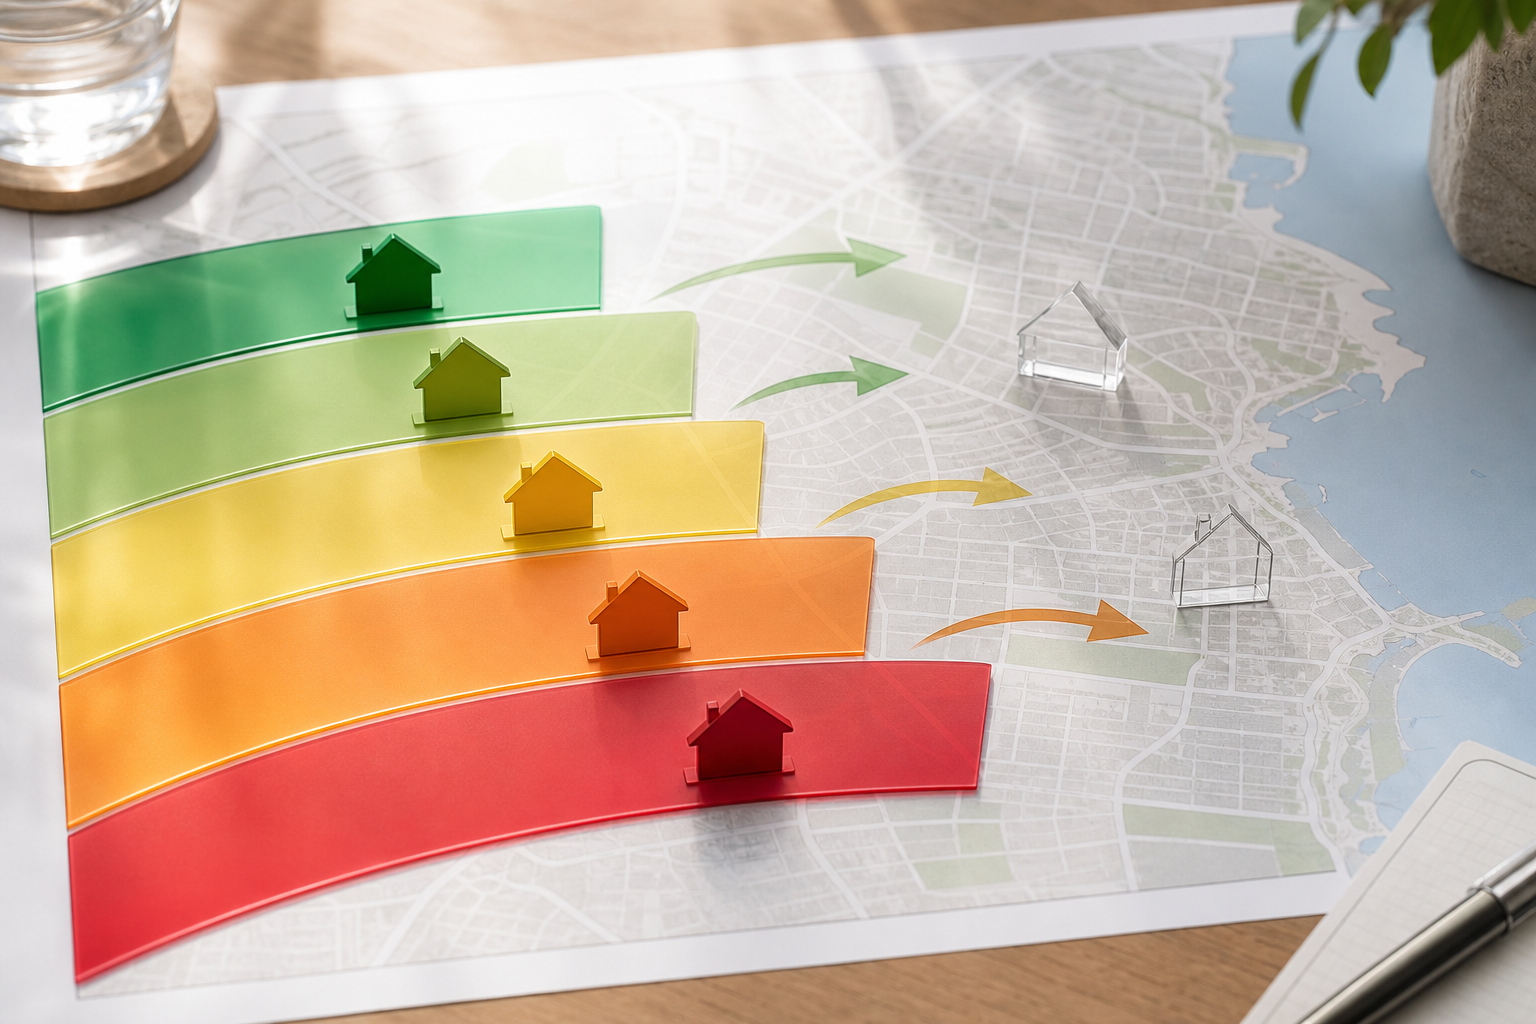
A. Comparing options by LVR band
| Situation / LVR band | Likely refinance options | Main levers this week |
|---|---|---|
| ≤75% LVR | Broad lender choice, strong pricing | Full refi, fix/part‑fix, restructure splits |
| 75–80% LVR | Most lenders okay, some shading | Refi or renegotiate; avoid tipping over 80% |
| 80–90% LVR (tight) | Limited lenders, higher scrutiny, LMI | Negotiate with current bank; targeted partial refi |
| >90% LVR (very tight) | Refi often impractical | Ride it out, restructure with existing bank, buffers |
In this article we focus on the tight bands – 80–95%.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Can I refinance my Bronte home loan if my LVR is over 90%?▾
What should I do first if Bronte property values have dropped?▾
Is it worth paying LMI again to refinance in a soft market?▾
How can I reduce risk if I can’t refinance my Bronte mortgage?▾
Should I sell my Bronte property if I’m stuck at a high LVR?▾
Request a strategy call
Confidential consultation with a triple-qualified advisor — commercial, SMSF, equipment and development finance.