Article
Sydney’s Eastern Suburbs Postcode Risk: What Banks Really Worry About
Banks quietly mark parts of Sydney’s Eastern Suburbs as higher-risk postcodes. That can cap your LVR, shrink borrowing power or derail a pre-approval. Here’s what they look at, which areas get flagged, and how to structure a deal that still works this week.
Key Takeaway
Banks treat some Sydney Eastern Suburbs postcodes as higher risk, which can mean lower maximum LVRs (often 70–80% instead of 90–95%), tighter income shading, and more conservative valuations. These postcode risk lists focus on prestige suburbs, high-density unit clusters, and tiny apartments where resale is less certain. Borrowers can respond by adjusting property type or price point, sequencing lenders, and pre-testing valuations to keep purchases and refinances on track.
Watch the short answer
How ABN age can affect your chances with the banks
While you’re weighing postcode risk in the Eastern Suburbs, this video shows how your ABN age can quietly shape what banks will lend.
Read the transcript
Most banks have a rigid rule: if your ABN hasn't been active for two full years, you can't get a home loan. But if your trade business has been booming for 12 months, why should your family wait to buy a house? We have direct access to alternative doc lenders who accept 6 to 12 months of active trading backed by clean business bank deposits. Stop waiting for arbitrary timelines. DM me 'GROWTH' to look at your options.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Tailored Loans Sydney
Banks quietly mark parts of Sydney’s Eastern Suburbs as higher-risk postcodes. That can cap your LVR, shrink borrowing power or derail a pre-approval. Here’s what they look at, which areas get flagged, and how to structure a deal that still works this week.
Read the full guide on tailoredloans.sydneyBanks do use postcode risk lists in Sydney’s Eastern Suburbs, and they get cautious fastest on prestige houses, high‑density unit clusters and small apartments. That usually shows up as lower LVR caps, tougher income tests and more conservative valuations, not an outright “no”. If you know where the tripwires are, you can adjust your lender, structure or property target this week and still move.
How postcode risk lists actually work in the East
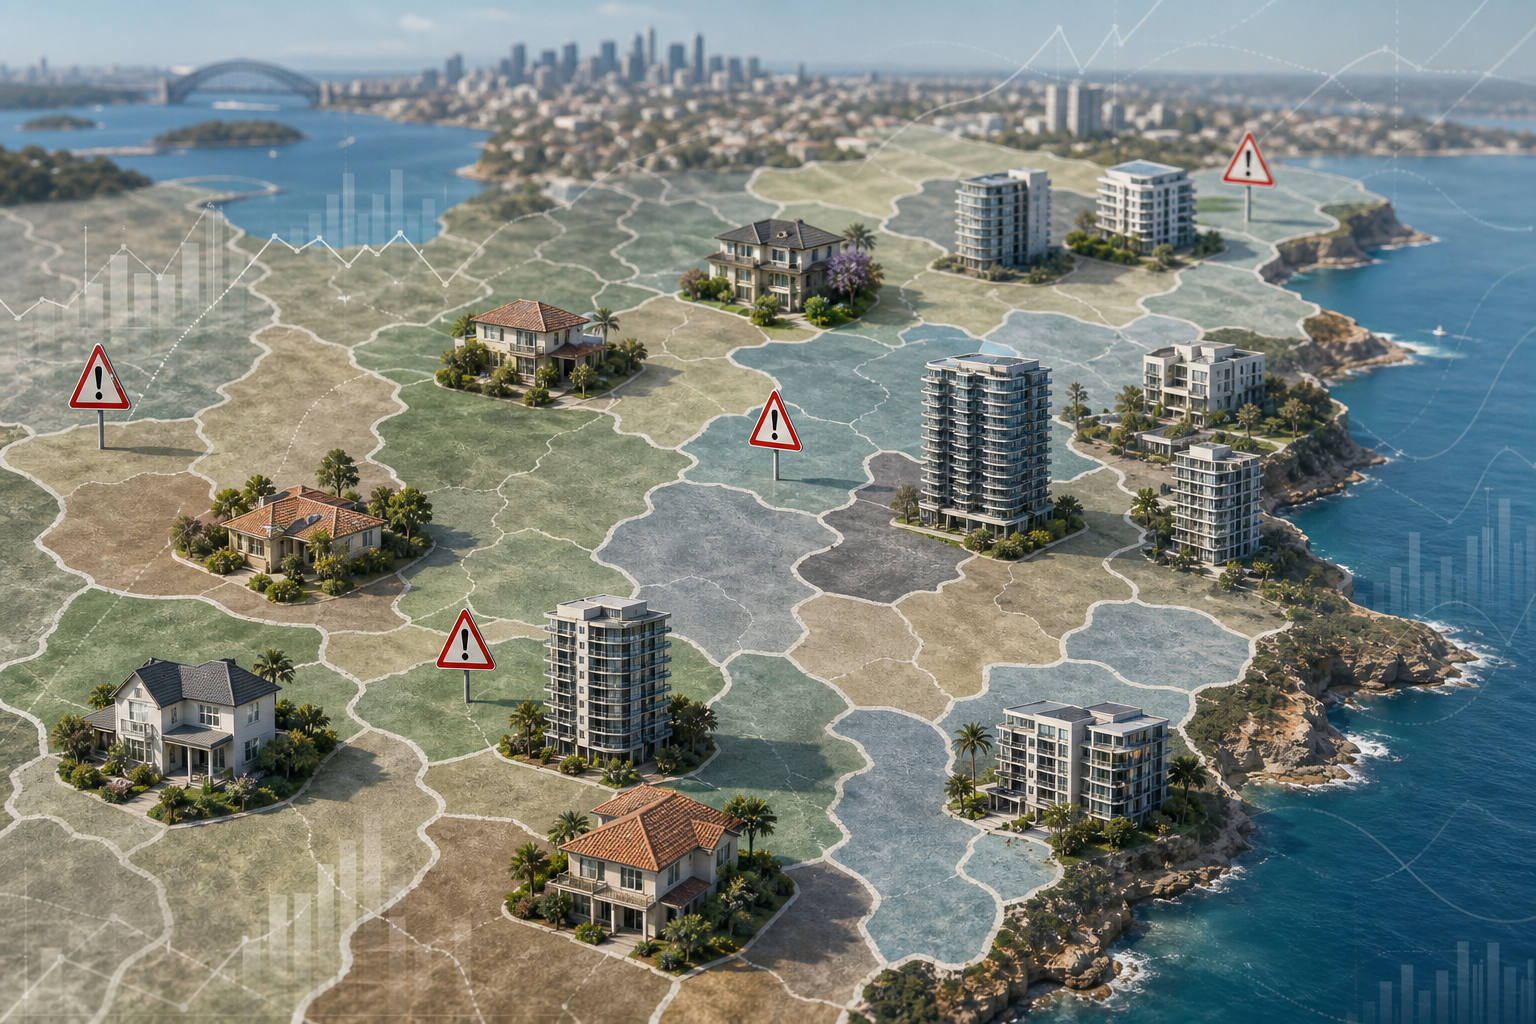
Lenders keep internal lists flagging suburbs and buildings where they see higher risk. In the Eastern Suburbs, that risk is less about crime and more about price volatility, density and resale depth.
On a flagged postcode, banks might:
- Cap LVRs (for example, 70–80% instead of 90–95%).
- Tighten policy on apartments (minimum size, building age, high‑density rules).
- Shade income more heavily for self‑employed or variable earners.
- Require full valuations instead of desktop or AVM.
- Be stricter on jumbo exposure above about $2–3m per property.
For a deeper national overview of how these lists work, see How Postcode Risk Lists Quietly Change Your Home Loan Options.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Do all banks use the same postcode risk list in the Eastern Suburbs?▾
Can a postcode move off the risk list?▾
How early should I check postcode policy before an Eastern Suburbs auction?▾
Request a strategy call
Confidential consultation with a triple-qualified advisor — commercial, SMSF, equipment and development finance.