Article
How To Build Cash Buffers And Credit Limits That Actually Work
A practical Australian guide to setting cash buffers and business credit limits that protect your home, your business and your sleep – without parking too much money in low‑return cash.
Key Takeaway
This article explains how Australian households and small businesses should size cash buffers and working capital credit limits, recommending three to six months of essential costs for stable PAYG income and six to twelve months for self-employed or volatile earnings. It outlines a simple three‑bucket buffer system, shows how to calculate overdraft limits from cash conversion cycles, and quantifies how oversized limits can hurt home loan borrowing power. Readers get a step‑by‑step process to reset buffers and limits within a week.
Watch the short answer
How ABN age can affect your chances with the banks
While you’re working out buffers and limits, this video shows how your ABN age can shape your home and business lending options.
Read the transcript
Most banks have a rigid rule: if your ABN hasn't been active for two full years, you can't get a home loan. But if your trade business has been booming for 12 months, why should your family wait to buy a house? We have direct access to alternative doc lenders who accept 6 to 12 months of active trading backed by clean business bank deposits. Stop waiting for arbitrary timelines. DM me 'GROWTH' to look at your options.
General information only, not personal advice. Your situation is assessed before any recommendation.
Designing buffers, reserves and credit limits starts with one goal: you want enough cushion that surprises don’t break you, but not so much dead cash or unused limit that it quietly drags on returns and borrowing power. In practice for most Australians, that means 3–6 months of essential costs in cash or offset for stable PAYG income, and 6–12 months for self‑employed or volatile income earners, plus tightly‑designed business credit limits sized to real working capital swings.
Here’s how to turn that into a plan you can actually implement this week.
1. What a “cash cushion” really is (and what it isn’t)
A cash cushion is the combination of:
- Immediate cash – money you can access within seconds or a day.
- Short‑term reserves – cash or true offset balances earmarked for emergencies or volatility.
- Stand‑by credit – overdrafts, lines of credit and cards designed as backup, not permanent funding.
A good design answers three questions:
- How many months of essential costs do you want covered?
- What mix of cash vs credit will you use?
- How will you stop that standby credit from becoming permanent debt?
These numbers are personal, but there are solid guardrails we’ll walk through.
2. Household buffers: simple rules that actually work
We already know from other parts of our knowledge hub that:
- Stable PAYG borrowers are usually safer with at least 3–6 months of essential living costs plus loan repayments in cash or true offset (not redraw or volatile investments) [facts 10, 16].
- Self‑employed or irregular income borrowers should aim for 6–12 months [facts 7, 10].
Let’s build on that and make it practical.
2.1 Define “essential costs” properly
Don’t use your bank statement total. Strip back to:
- Home loan and investment loan repayments (on a stressed rate – at least 3% above today, similar to APRA’s buffer).
- Rent (if applicable).
- Utilities, food, transport, insurances.
- School fees and absolutely necessary medical costs.
Ignore holidays, eating out, new cars. Your buffer is for staying afloat, not living large.
Example – PAYG couple in Sydney
- Stressed home loan repayment (6.5%): $3,800/month.
- Other essential costs: $3,200/month.
- Total essential: $7,000/month.
Reasonable buffer target:
- Minimum (3 months): $21,000.
- Safer (6 months): $42,000.
If they’re self‑employed with lumpy income, I’d be more comfortable at 6–9 months ($42,000–$63,000).
2.2 Where to hold your buffer
The key is access + safety + clean tax tracing:
- True offset account linked to your home loan is usually best.
- A high‑interest savings account works if you don’t have an offset.
- Avoid using redraw as your main buffer if you run a business – it blurs personal and business use and complicates tax and risk [facts 3, 4, 19].
If you’re considering using equity for projects like solar, renovations or investment, the priority is keeping a 3–6+ month household buffer intact even after the project spend [facts 5, 12, 18].
2.3 How much is “too much” in cash?
Warning signs you’re over‑buffered:
- You’re carrying high‑interest debt (credit cards, personal loans) while sitting on large cash.
- You’re ahead of all realistic emergency needs (say 12+ months) and also under‑invested.
A balanced approach:
- Build to your target months of cushion.
- Any surplus above that can go to debt reduction or long‑term investing based on your broader plan.
3. Business buffers: separating shock absorbers from working capital
Small business owners often muddle three very different needs:
- A household buffer so the family doesn’t ride every cashflow bump.
- A business buffer to absorb shocks (lost client, late payer, tax bill).
- Working capital finance (overdraft, line of credit, trade finance) to smooth timing differences.
Your life gets simpler when each job has its own tool.
For the bigger picture on structures and costs, see our guide on Working Capital Basics: Structures, Costs And Safe Limits For SMEs.
3.1 Household vs business buffers
As a business owner, you really want both:
- Household buffer: 6–12 months of essential living costs plus all personal loan repayments.
- Business buffer: at least 1–3 months of business operating costs (excluding big, planned projects).
Example – small consulting business
- Monthly business operating costs (wages, rent, software, insurance): $40,000.
- Target business buffer: 2 months = $80,000.
- Personal essential costs: $8,000/month.
- Target household buffer: 6 months = $48,000.
Combined target across accounts/offsets: $128,000.
You might decide:
- $80,000 in the business account/offset (purely business use).
- $48,000 in personal offset.
Clean separation matters for tax tracing and bank assessment [fact 19].
3.2 The three‑bucket buffer system
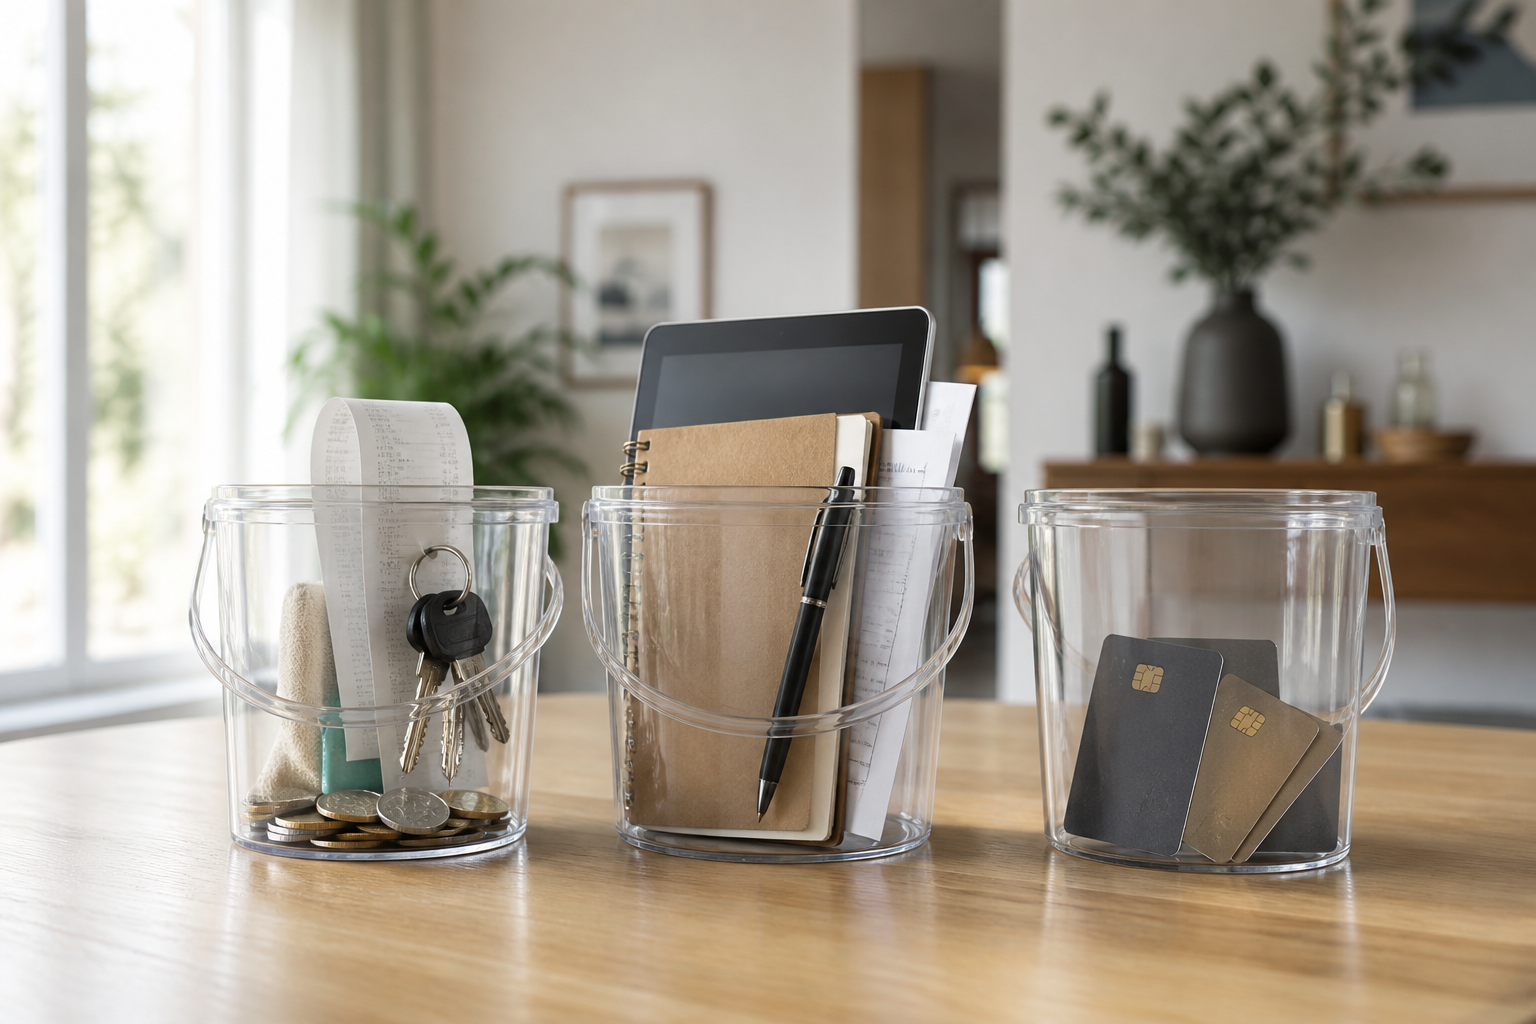
To keep things simple, use three buckets:
- Operating cash (Bucket A) – next 30 days of expenses.
- Short‑term buffer (Bucket B) – extra 1–2 months in the business account.
- Deep buffer (Bucket C) – another 3–9 months, often in a personal or business offset that you treat as untouchable without a conversation.
A practical rule:
- Bucket A + B = 2–3 months of business costs.
- Bucket C = household buffer plus any extra business shock reserve.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 7 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
How big should my cash buffer be as a PAYG employee in Australia?▾
How much cash should a small business keep in reserve?▾
How do I calculate the right overdraft limit for my business?▾
Is using my home loan redraw as a business buffer a good idea?▾
Do large credit card or overdraft limits hurt my home loan borrowing power?▾
Should I build a cash buffer before investing or paying off debt faster?▾
Request a strategy call
Confidential consultation with a triple-qualified advisor — commercial, SMSF, equipment and development finance.