
Article
How To Design A Business Overdraft That Scales With Your Cashflow
A structured overdraft shouldn’t be a guess or a permanent crutch. Here’s how to size, secure and review an overdraft so it flexes with your business, protects your home and doesn’t kill your future borrowing power.
Key Takeaway
This article explains how to design a structured overdraft that flexes with an Australian small business rather than acting as a permanent crutch. It outlines how to map cashflow cycles, separate permanent capital from short-term working capital, and set an overdraft limit typically below 15–20% of stable annual revenue. A worked example and review checklist show how to adjust limits and terms annually so the facility supports both business resilience and future home loan borrowing power.
Watch the short answer
How ABN age can affect your chances with the banks
While you’re weighing up the right overdraft size, this video shows how your ABN age can shape what banks will actually lend you.
Read the transcript
Most banks have a rigid rule: if your ABN hasn't been active for two full years, you can't get a home loan. But if your trade business has been booming for 12 months, why should your family wait to buy a house? We have direct access to alternative doc lenders who accept 6 to 12 months of active trading backed by clean business bank deposits. Stop waiting for arbitrary timelines. DM me 'GROWTH' to look at your options.
General information only, not personal advice. Your situation is assessed before any recommendation.
A structured business overdraft should cover short cash gaps, sit well below your annual revenue, and be reviewed at least yearly so it shrinks or grows with your business. It is not a permanent funding source for stock, fit‑outs or tax debts, and it should be designed alongside your home‑loan plans so the limit and security don’t quietly kill borrowing power.
In practice, that means three steps: 1) map your cash cycle, 2) carve out permanent capital into term loans, and 3) set a clear overdraft limit, utilisation range and review rhythm.
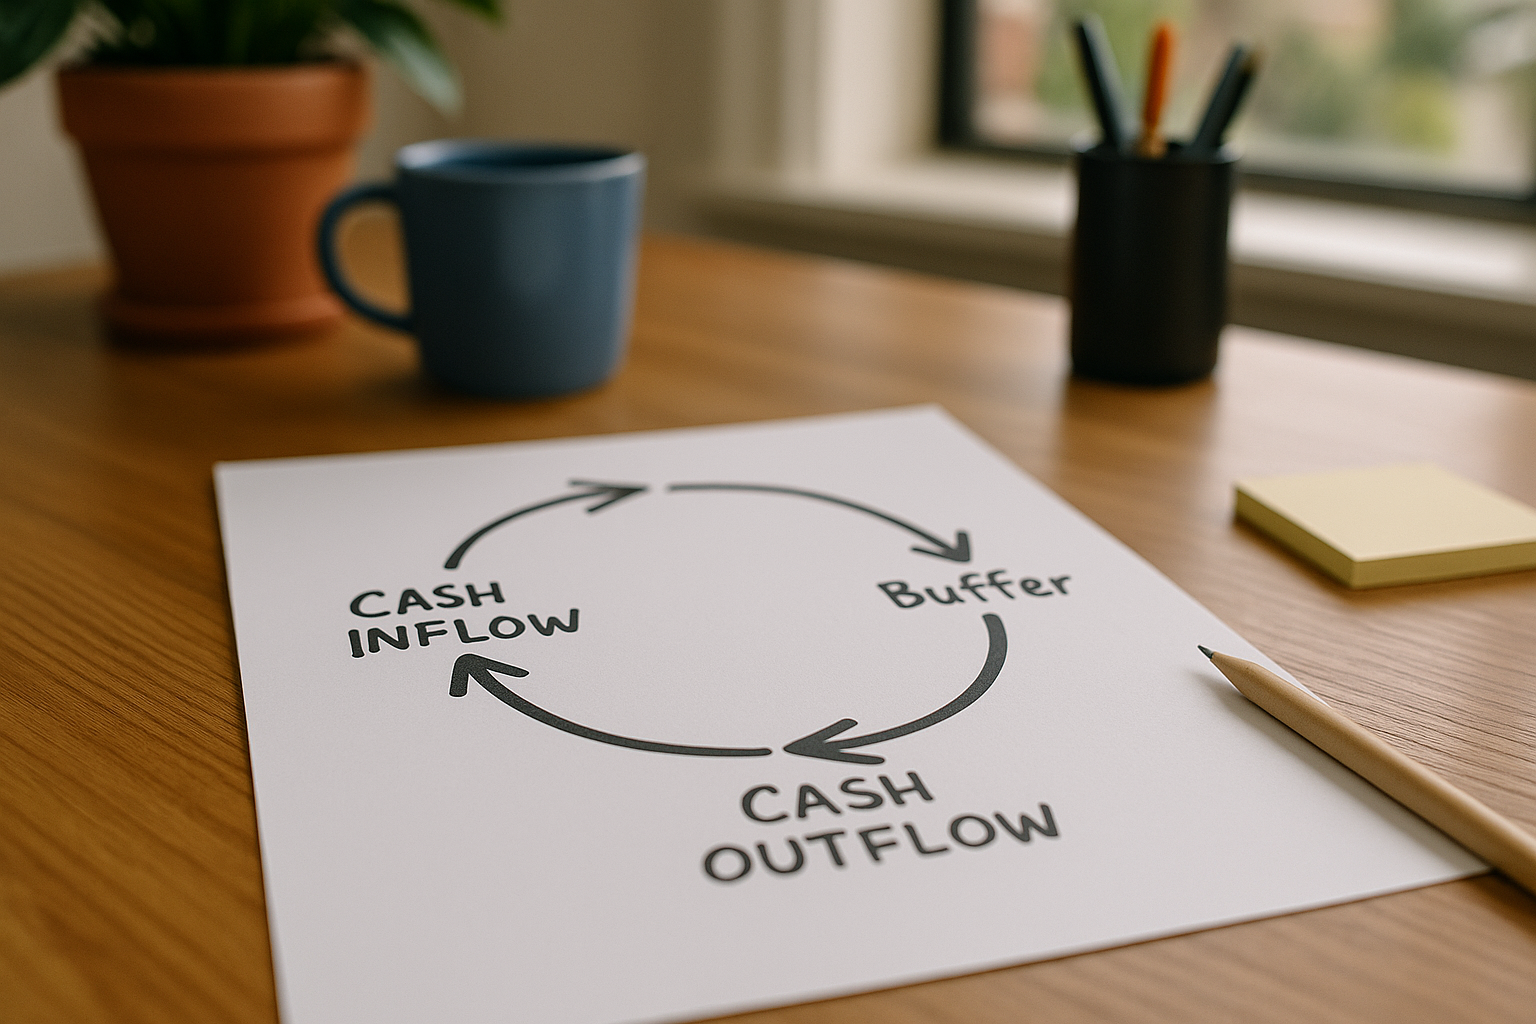
1. What a "structured" overdraft actually means
A lot of businesses simply accept whatever overdraft limit the bank offers at the start and then live with it for years. A structured overdraft is the opposite: it has a defined role, a sizing method, and rules for when it should change.
Core design principles
A well‑designed overdraft should:
- Fund timing gaps only – wages, GST/BAS, stock and debtor timing.
- Sit below permanent working capital needs – long‑life stock and fit‑outs belong in term loans.
- Be right‑sized to your revenue and volatility, not the maximum the bank will approve.
- Be reviewed annually and after big events (new site, major contract, downturn).
If your balance barely changes over 12–24 months, part of your facility is acting like permanent debt and should usually be converted to a term loan. This warning sign shows up again and again in hospitality and retail groups.
For a quick refresher on how overdrafts compare with other tools like trade finance and short‑term loans, see Working Capital Basics: Structures, Costs And Safe Limits For SMEs.
2. Sizing the overdraft: limits that move with revenue
Step 1: Map your cashflow cycle
Start with 12 months of data:
- Weekly or monthly sales.
- Debtor days (how long customers take to pay).
- Stock and supplier payment timing.
- Payroll, rent and BAS dates.
Plot your worst cash month. The size of the gap between outflows and inflows in that period is the starting point for your overdraft design.
Step 2: Separate permanent from temporary needs
Permanent capital includes:
- Base stock levels you always carry.
- Fit‑outs, equipment and vehicles.
- Any losses you’re still carrying from a past hit.
These are better funded with term loans or equipment finance, not a revolving overdraft. This separation step is critical and underpins our work on How To Align Working Capital, Equipment Loans And Leases To Cashflow.
Step 3: Use practical sizing rules
Indicative rules many mature SMEs use:
- Overdraft limit: often no more than 10–15% of stable annual revenue.
- Ability to clear: the overdraft should be capable of being brought back close to zero from trading surpluses within 12–24 months.
If you need more than that, it’s often a sign you’re under‑capitalised or using the overdraft to fund losses.
Worked example: designing a limit
Assume:
- Annual revenue: $3.0m (ex‑GST).
- Average debtor days: 45.
- Stock turns: every 30 days.
- Fixed monthly costs (wages, rent, overheads): $140,000.
In the worst month, you must fund roughly 1.5 months of fixed costs plus a layer of stock and GST before debtors pay:
- Fixed costs: 1.5 × $140,000 ≈ $210,000.
- Short‑term stock and GST swing: say $40,000.
Indicative overdraft design gap: about $250,000. On $3.0m revenue, that’s ~8.3% of revenue – reasonable for a business with modest volatility.
If your bank had set a $450,000 limit years ago and you’re sitting at $380,000 drawn most months, that’s a sign you should:
- convert, say, $200,000 to a term loan; and
- reset the overdraft to ~$250,000 with a clear target to use it only for swings.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
How big should my business overdraft limit be?▾
How often should I review my overdraft?▾
Is using my home loan redraw instead of an overdraft a good idea?▾
What’s the difference between an overdraft and a term working capital loan?▾
Can my overdraft affect my chances of getting a home loan?▾
Request a strategy call
Confidential consultation with a triple-qualified advisor — commercial, SMSF, equipment and development finance.