Article
Funding The Second Site: Working Capital Moves That Keep You Safe
Opening a second site? Here’s a decision‑grade working capital plan so you don’t blow cashflow, over‑gear the group, or quietly risk the family home.
Key Takeaway
When opening a second business location, owners should separate fit-out, launch stock, and early trading losses, then fund each with different facilities to avoid over-gearing short-term working capital. A practical rule is to hold 3–6 months of new site fixed costs in cash buffers and ensure total working capital debt remains serviceable within 12–24 months from normal trading. Mapping both sites’ cashflows and aligning facilities to asset life helps protect the family home and borrowing power while scaling.
Opening a second location safely means planning working capital up front: separate the cash for fit‑out, opening stock, and early trading losses, then match each bucket to the right type of finance and a realistic buffer. If you can’t show on paper that both sites survive 6–12 weak months without raiding your home loan or ATO money, the plan isn’t ready yet.
Step 1: Map the real cash needs of the second site
Don’t start with “what will the bank give me?”. Start with “what will this site actually burn through?”
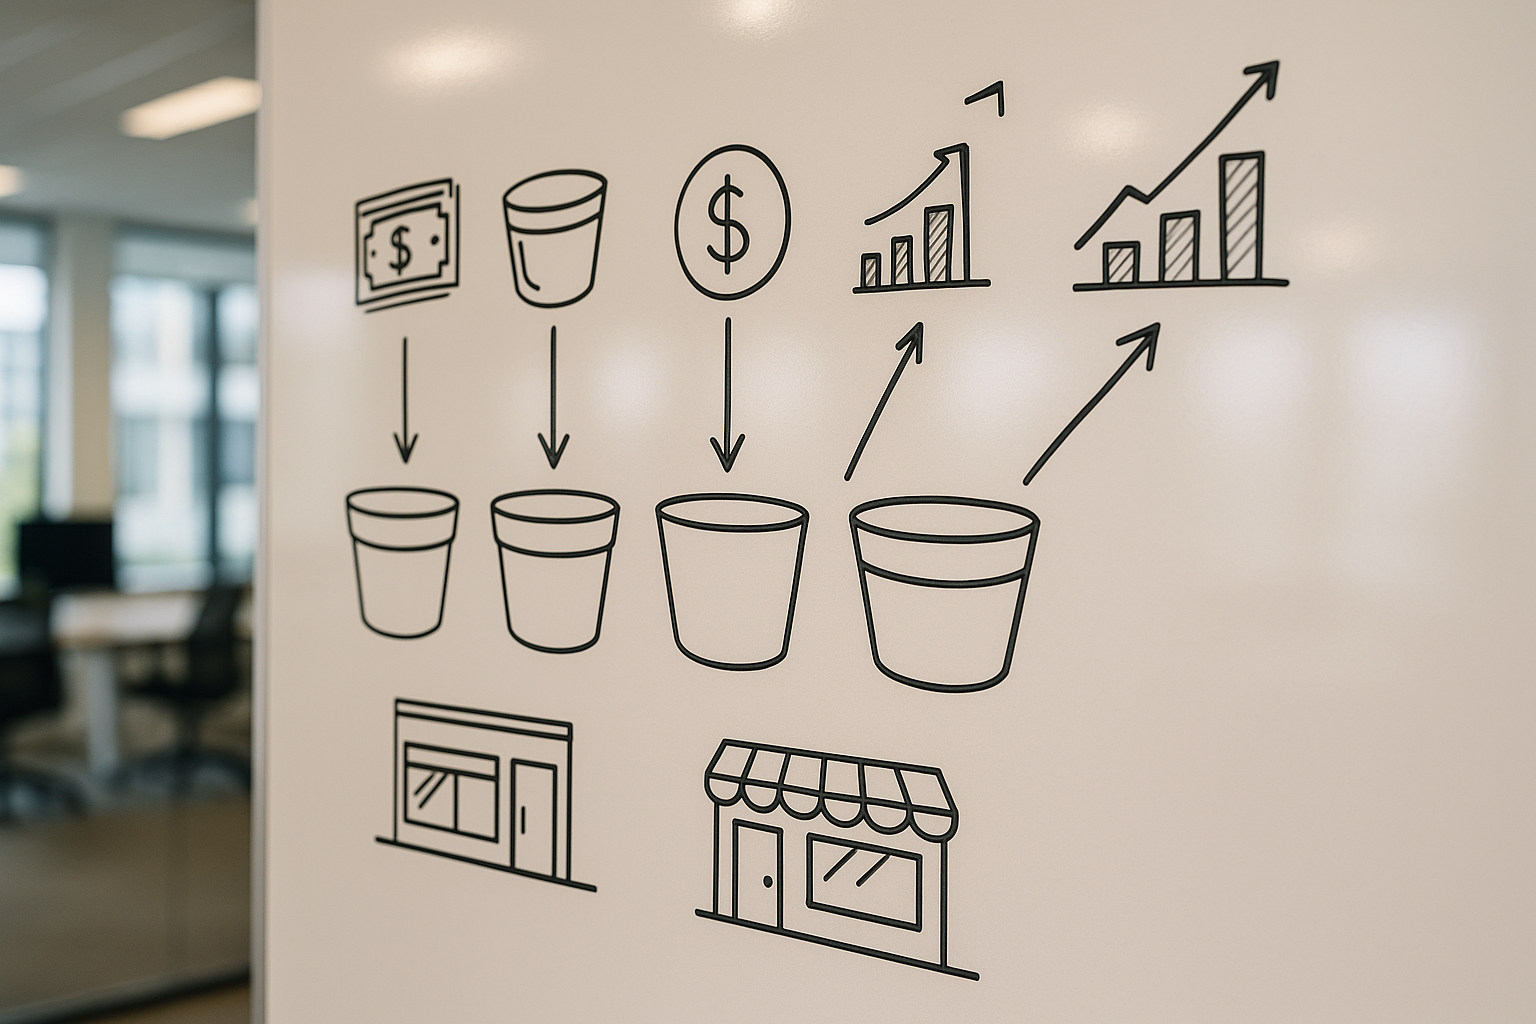
Break it into four buckets:
- Fit‑out and equipment – once‑off, long‑life items.
- Opening stock / pre‑launch costs – once, but shorter‑life.
- Working capital for trading – the day‑to‑day gap between paying suppliers and getting paid.
- Buffer for slow ramp‑up – the ugly first 6–12 months.
A quick worked example
Say you’re opening a second café or clinic:
- Fit‑out and equipment: $300,000 (life 5–7 years)
- Opening stock / pre‑launch marketing: $60,000
- Fixed monthly burn (rent, wages, utilities, basics): $70,000
- You expect it to be cashflow break‑even in month 9.
If you assume 9 months to break‑even and want a 3‑month extra buffer, your working‑capital‑plus‑buffer need is roughly:
(9 + 3) × $70,000 = $840,000
That doesn’t mean you borrow $840k as working capital – but it does mean you need a clear plan for how that gap is funded and repaid.
For a deeper overview of structures and safe leverage, see Working Capital Basics: Structures, Costs And Safe Limits For SMEs.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
How big should my overdraft be for a second location?▾
Should I use home loan redraw to fund my second business site?▾
When is it safer to delay opening a second location?▾
Request a strategy call
Confidential consultation with a triple-qualified advisor — commercial, SMSF, equipment and development finance.