
Article
How to Time SMSF and Personal Property Sales for CGT and Cashflow
A practical guide to timing SMSF and personal property sales so you don’t blow up capital gains tax, pensions or household cashflow under the new rules.
Key Takeaway
Synchronising SMSF and personal property sales can reduce capital gains tax and prevent cashflow shocks by aligning gains with lower-income years and pension phases. With upcoming CGT and negative gearing reforms from 1 July 2027, the timing of disposals across entities matters more than ever. Investors should map all likely gains, pensions, and loan commitments over a 3–5 year horizon, then deliberately stage settlements to smooth tax and fund debt payouts without raiding buffers.
Watch the short answer
Can you still buy a property if your tax isn’t done yet?
If tax delays are holding you back, this explains how lenders may assess income without a final return.
Read the transcript
think you can't buy a property this year because your accountant hasn't finalised your 2026 tax returns, think again. If you are a freelancer, a contractor or a growing business, that means months of lost opportunity. We use alternative documentation pathways that completely bypass the ATO delay. We assess your true borrowing capacity using the last 6 months of your business bank deposits, getting you approved while your competitors are still waiting on paperwork. Stop waiting on tax portals to dictate your property goals. message me 'ALTDOC' to fast track your FY27 approval.
General information only, not personal advice. Your situation is assessed before any recommendation.
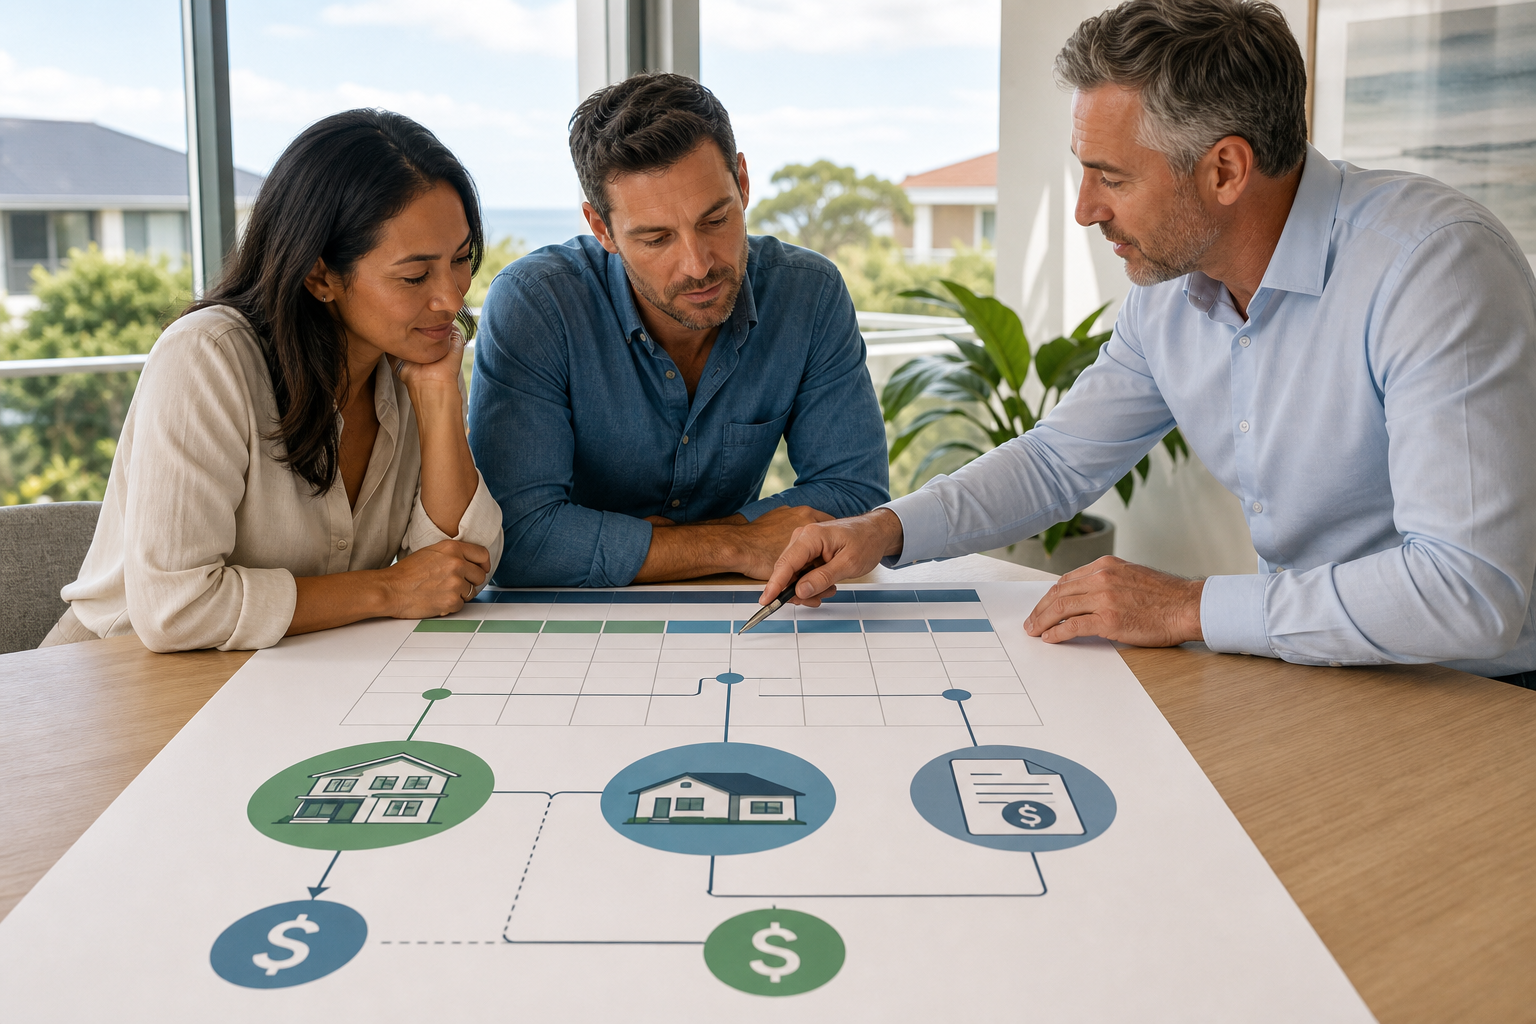
Synchronising SMSF and personal property sales means deliberately timing each sale and settlement so you minimise capital gains tax (CGT), keep pensions flowing, and avoid a cash crunch when loans are repaid. You’re not trying to “beat” the ATO — you’re matching gains, income and cash needs across your SMSF, personal name and any entities.
Quick answer: build a 3–5 year calendar of likely sales, estimate CGT and loan payouts for each, then choose which property sells first, and in which financial year, based on: 1) who has the lowest tax rate, 2) when SMSF pensions start or ramp up, and 3) when you can safely free cash without gutting buffers.
Step 1: Map your assets, gains and loans by entity
Start with one page that covers everything:
- Personal home (usually CGT‑free, but may have partial main residence exemption).
- Personal investment properties (subject to CGT and negative gearing reforms from 2026–27).
- SMSF property (different CGT rules once in pension phase).
- Business or company‑held property.
- Loans and expiry dates (home, investment, SMSF LRBA, business loans).
For each property, jot down:
- Likely sale price range.
- Estimated cost base.
- Rough gain = price – cost base – selling costs.
- Loan payout required at settlement.
You now have a rough CGT and cash “map” across entities.
If your SMSF has geared property, combine this step with an exit plan using /insights/exit-planning-smsf-property-pensions-loans.
Step 2: Understand how CGT differs for SMSF vs personal
Personal name or trust
- Current rules: 50% CGT discount after 12 months for individuals/trusts (subject to 2026–27 reforms).
- From 1 July 2027 (proposed): shift towards minimum 30% tax on many gains and CPI indexation instead of the 50% discount.
- Losses and negative gearing on established residential property will be harder to use for many investors.
SMSF
- Accumulation phase: gains effectively taxed at up to 15% (with a one‑third CGT discount for assets held >12 months).
- Pension phase: gains on assets supporting retirement phase income streams can be 0% up to your transfer balance cap (subject to ECPI rules).
Implication: after 2027, the relative advantage of holding and selling long‑term property in an SMSF (especially in pension phase) typically increases compared with selling in your own name.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Should I always sell SMSF property after I retire?▾
Is it better to sell personal or SMSF property first?▾
Can I move a property from personal ownership into my SMSF instead of selling?▾
Request a strategy call
Confidential consultation with a triple-qualified advisor — commercial, SMSF, equipment and development finance.