
Article
Strategic mortgage broking for Eastern Suburbs families and professionals
How a strategic Eastern Suburbs broker helps families and professionals turn today’s loan decision into a 10–15 year property and tax‑smart plan they can act on this week.
Key Takeaway
Strategic mortgage broking for Eastern Suburbs families means designing home loans as part of a 10–15 year property and tax plan, not just chasing today’s sharpest rate. With Woollahra’s median weekly mortgage at $900 versus $560 for Greater Sydney, careful stress-testing at 3% above current rates and keeping repayments under 30–35% of net income is critical. The key action is to map your next two property moves and align a long-term broker relationship around that roadmap this week.
Watch the short answer
How ABN age can affect your chances with the banks
Find out why many lenders care how long your ABN has been active before they lend.
Read the transcript
Most banks have a rigid rule: if your ABN hasn't been active for two full years, you can't get a home loan. But if your trade business has been booming for 12 months, why should your family wait to buy a house? We have direct access to alternative doc lenders who accept 6 to 12 months of active trading backed by clean business bank deposits. Stop waiting for arbitrary timelines. DM me 'GROWTH' to look at your options.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Tailored Loans Sydney
How a strategic Eastern Suburbs broker helps families and professionals turn today’s loan decision into a 10–15 year property and tax‑smart plan they can act on this week.
Read the full guide on tailoredloans.sydneyBusy Eastern Suburbs families and professionals should use a strategic mortgage broker to design a 10–15 year property and loan plan, not just find a bank willing to say “yes” this month. Done properly, your broker becomes a long‑term partner who maps likely moves, structures debt around tax and cashflow, and keeps repayments under practical stress limits so you can sleep at night.
Quick answer: what “strategic broking” actually means
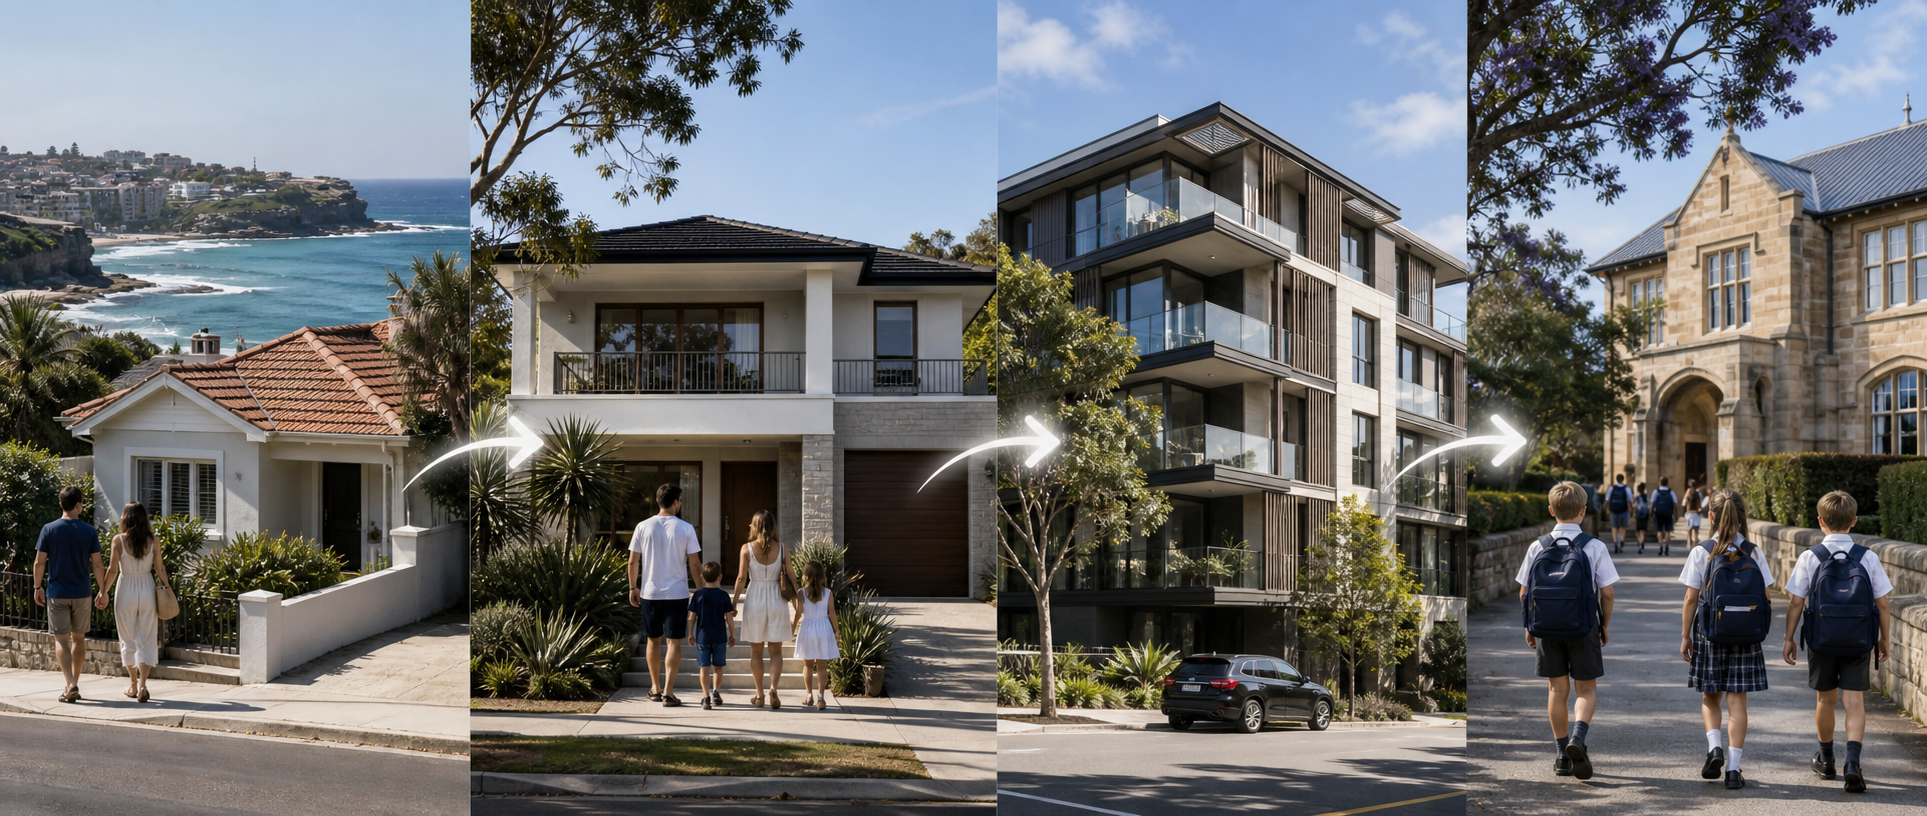
Strategic mortgage broking in Sydney’s East is a three‑part discipline:
- Roadmap first – map 10–15 years of likely moves and life events before picking a lender.
- Structure over rate – design splits, entities and buffers around tax, school fees, business and future investments.
- Long‑term reviews – keep a standing relationship with annual and event‑based check‑ins, not one‑off transactions.
For a deeper roadmap framework, pair this with /insights/long-term-property-mortgage-planning-eastern-suburbs.
Why Eastern Suburbs borrowers can’t just “chase a cheap rate”
High debt, high incomes, low time
Woollahra’s median weekly mortgage was about $900 in 2021, versus $560 for Greater Sydney. On a $2–4m mortgage, a 1% rate mistake can mean $20,000–$40,000 a year in extra interest.
Add in:
- lumpy bonuses and business income
- school fees, renovations and aging‑parent support
- future investments and potential negative gearing reforms
…and you can see why a simple “lowest rate” approach is dangerous.
A practical ceiling for total home and investment repayments in the East is 30–35% of net income, even if lenders will approve more (facts 6, 16, 20). A strategic broker builds your plan around that, not around maximum borrowing power.
Worked example: stress‑testing a Double Bay family
- Combined net income: $420,000 p.a. (approx. $25,000 per month)
- Target repayment band (30–35% of net): $7,500–$8,750/mth
- Loan required for family home: $3.2m, 30‑year P&I
At an indicative 6.0% p.a.:
- Repayments ≈ $19,180 p.m. – already around 77% of income. Not viable.
A strategic broker instead might:
- reduce purchase price or increase deposit
- use interest‑only for 3–5 years on part of the debt
- lock in standalone splits so future investments don’t cross‑collateralise
- model a downside scenario with one income cut and rates 3% higher (facts 7, 17)
The result is a smaller, safer first step that still fits a 10–15 year plan.
What a strategic Eastern Suburbs broker actually does
1. Builds a long‑term property roadmap
Strategic broking starts with questions like:
- “Where are you living in 3, 7 and 15 years?”
- “When do school fees and renovations hit?”
- “Will you run a practice, consultancy or small business from year 5 or 10?”
Then the broker maps likely moves – upgrade, renovate, buy an investment, help kids – and layers a loan strategy over that. If you haven’t done this yet, see /insights/10-15-year-property-mortgage-plan-eastern-suburbs-family.
2. Designs the loan structure, not just the lender list
A strategic broker will usually:
- Ring‑fence each property with its own loans and splits, avoiding unnecessary cross‑collateralisation (facts 9, 18).
- Separate home, investment and business borrowing for tax and flexibility (fact 14).
- Use offset accounts and buffers instead of running cash through redraw.
- Treat short‑term or private lending as temporary scaffolding, with a clear exit (fact 19).
That structure is often more valuable than a tiny rate discount.
3. Integrates tax and cashflow insight
Because interest deductibility depends on what the funds are used for (fact 12), not just who owns the property, a broker with tax skills can:
- keep non‑deductible home debt as low as possible over time
- protect future interest deductibility for investments and business
- plan salary and profit distributions 12–24 months before a big purchase (fact 11)
This is where a CPA‑grade broker can act like your family CFO, aligning your tax and lending strategies in one conversation.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
What is a “10–15 year loan strategy” in practice?▾
How often should I review my loans with a strategic broker?▾
Do I really need a local Eastern Suburbs broker?▾
How does a CPA‑qualified broker actually help my loan strategy?▾
Is it risky to rely on interest‑only loans as part of a long‑term plan?▾
Request a strategy call
Confidential consultation with a triple-qualified advisor — commercial, SMSF, equipment and development finance.