Article
Self‑Employed in Alexandria: Make Messy Accounts Bank‑Ready Fast
Self‑employed in Alexandria with messy books? Here’s a one‑week plan to turn chaotic accounts into a clear, bankable home‑loan story – without pausing your business.
Key Takeaway
Self-employed borrowers in Alexandria can still get a strong home loan approval even with messy accounts by cleaning up the last two years of financials, separating business and personal spending, and preparing clear “normalising adjustments” such as one-off costs or COVID support. Lenders typically stress-test income with a 3% serviceability buffer and focus on taxable profit rather than drawings. A one-week bookkeeping tidy‑up and short written explanation can materially lift borrowing power and reduce approval risk.
Watch the short answer
How ABN age can affect your chances with the banks
Once your accounts are in shape, this video shows how the age of your ABN can still influence what banks will and won’t consider.
Read the transcript
Most banks have a rigid rule: if your ABN hasn't been active for two full years, you can't get a home loan. But if your trade business has been booming for 12 months, why should your family wait to buy a house? We have direct access to alternative doc lenders who accept 6 to 12 months of active trading backed by clean business bank deposits. Stop waiting for arbitrary timelines. DM me 'GROWTH' to look at your options.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Tailored Loans Sydney
Self‑employed in Alexandria with messy books? Here’s a one‑week plan to turn chaotic accounts into a clear, bankable home‑loan story – without pausing your business.
Read the full guide on tailoredloans.sydneySelf‑employed in Alexandria with chaotic accounts can still get a solid home loan approval if you do three things: clean up the last two years of numbers, separate business and personal spending, and clearly explain any weird swings or one‑offs. Lenders don’t need perfection – they need a bankable story that lines up across your tax returns, BAS and bank statements.
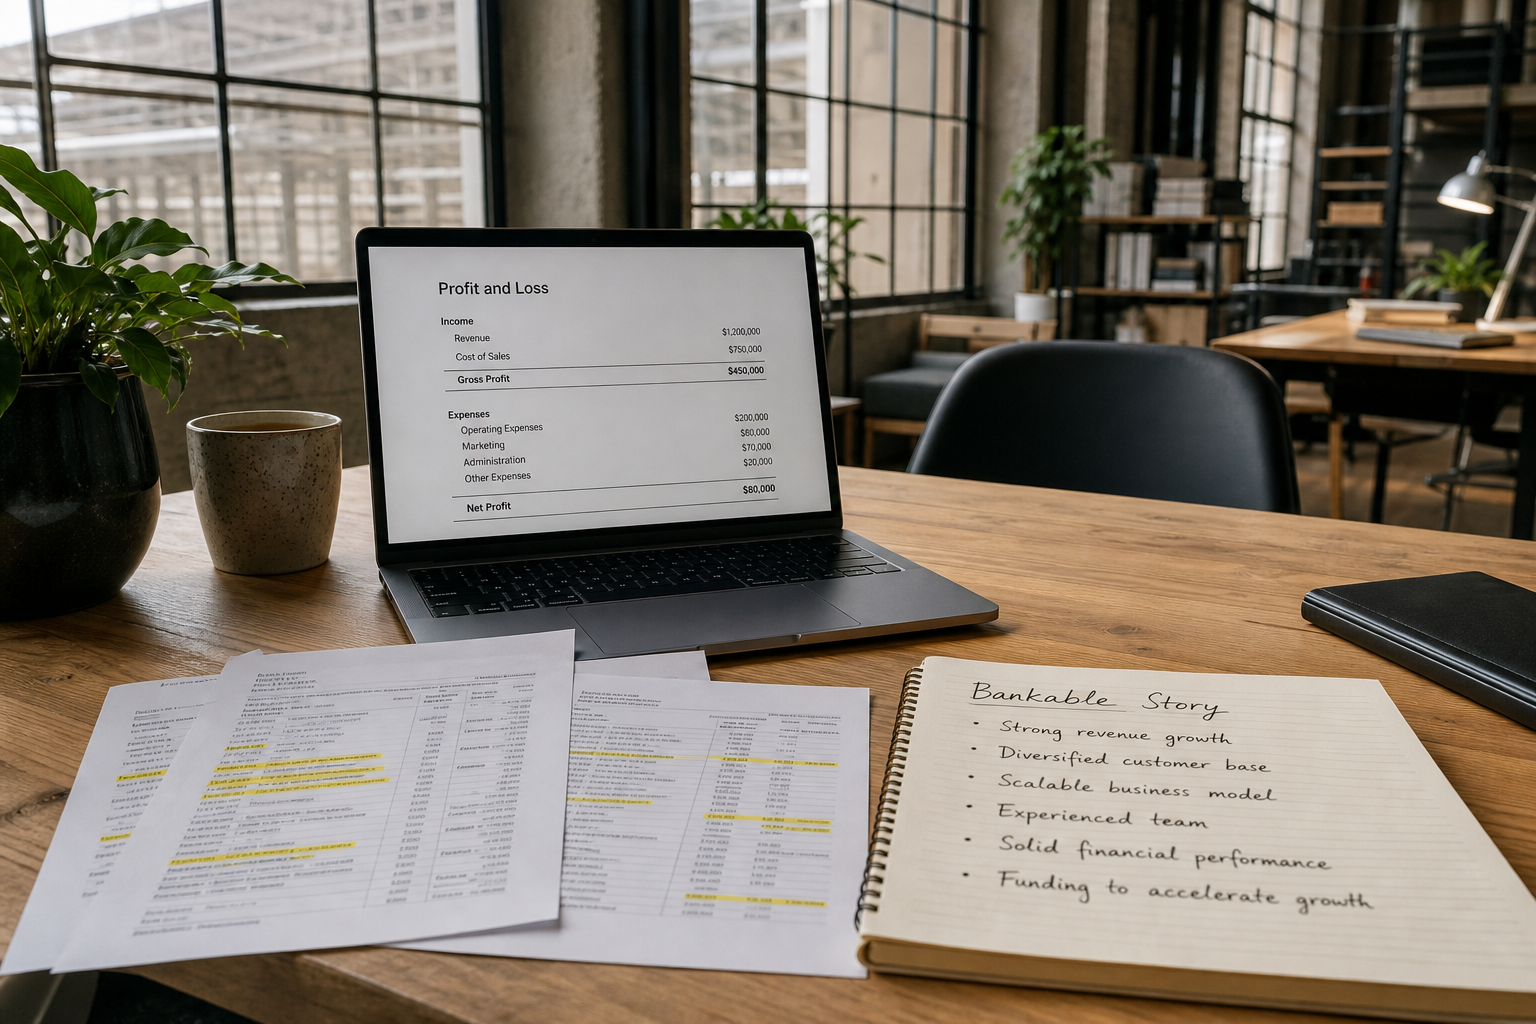
Step 1: Get two years of numbers lender‑ready
For most banks, the backbone of a self‑employed assessment is your last two years of tax returns and financial statements.
Aim for:
- Two full financial years lodged with the ATO.
- Profit and loss and balance sheet for the same periods.
- BAS and business bank statements that broadly support those numbers.
If one year is clearly weaker, some lenders will use the most recent year only if it’s higher and stable; others will average the two or even shade the latest down if turnover has dropped.
Worked example (indicative only):
- 2023 taxable profit: $115,000
- 2024 taxable profit: $145,000
A common approach is to average: $130,000. With an APRA‑style 3% buffer on rates and standard living expenses (HEM), that might support roughly a $650k–$800k loan on principal & interest, depending on other debts and dependants. The same business shown at $90k–$110k on paper could easily cut that by $150k–$200k.
If your returns aren’t lodged yet, don’t rush them just to “get the loan done”. The timing question alone can swing your borrowing power for two years – we unpack that in detail for Bronte business owners here: /insights/timing-tax-returns-bronte-small-business-home-buyers.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Do I need a full audit before applying for a home loan?▾
Will writing off everything for tax kill my borrowing power?▾
Can I get a home loan if last year’s business profit was terrible?▾
Request a strategy call
Confidential consultation with a triple-qualified advisor — commercial, SMSF, equipment and development finance.