Article
Should You Rent, Rentvest or Move Home Before Settlement?
Clear, decision-grade guide to choosing between renting, rentvesting or moving back home while you wait for your off-the-plan property to settle.
Key Takeaway
Home buyers waiting for off-the-plan settlement should compare three options: renting, rentvesting, or moving back home, using clear cashflow tests. With housing costs a key inflation driver and rates still elevated, keeping total repayments and rent under 30–35% of after-tax income and holding at least three months of housing costs in cash is prudent. The most robust choice usually offers maximum flexibility if the build is delayed and leaves a solid buffer at settlement.
Watch the short answer
Private lending isn’t always a desperation move
Wondering if private lending is only for trouble This video reframes when it can be a smart tool.
Read the transcript
Private lending isn't a desperation move. It is a sophisticated tool used by elite property investors to execute at lightning speed. When an undervalued asset hits the market, waiting months for institutional red tape means losing the deal. Private capital bypasses the standard bureaucracy, focusing purely on asset backing so you can close the transaction in days and exit cleanly later. Move faster than the market. DM me 'PRIVATE' to connect.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Tailored Loans Sydney
Clear, decision-grade guide to choosing between renting, rentvesting or moving back home while you wait for your off-the-plan property to settle.
Read the full guide on tailoredloans.sydneyIf you’re waiting for an off‑the‑plan settlement, you basically have three choices for the next 1–3 years: keep renting, start rentvesting, or move back in with family. The right answer is the option that (1) keeps your total housing costs manageable under higher rates, (2) gives you flexibility if the build is delayed, and (3) leaves you with a solid cash buffer on settlement day.
Quick answer: if cash is tight or you’re unsure about build timing, favour the cheapest flexible option (often moving home or a simple rental). Consider rentvesting only if you can still pass a 3% rate buffer and keep a 3–6 month cash buffer.
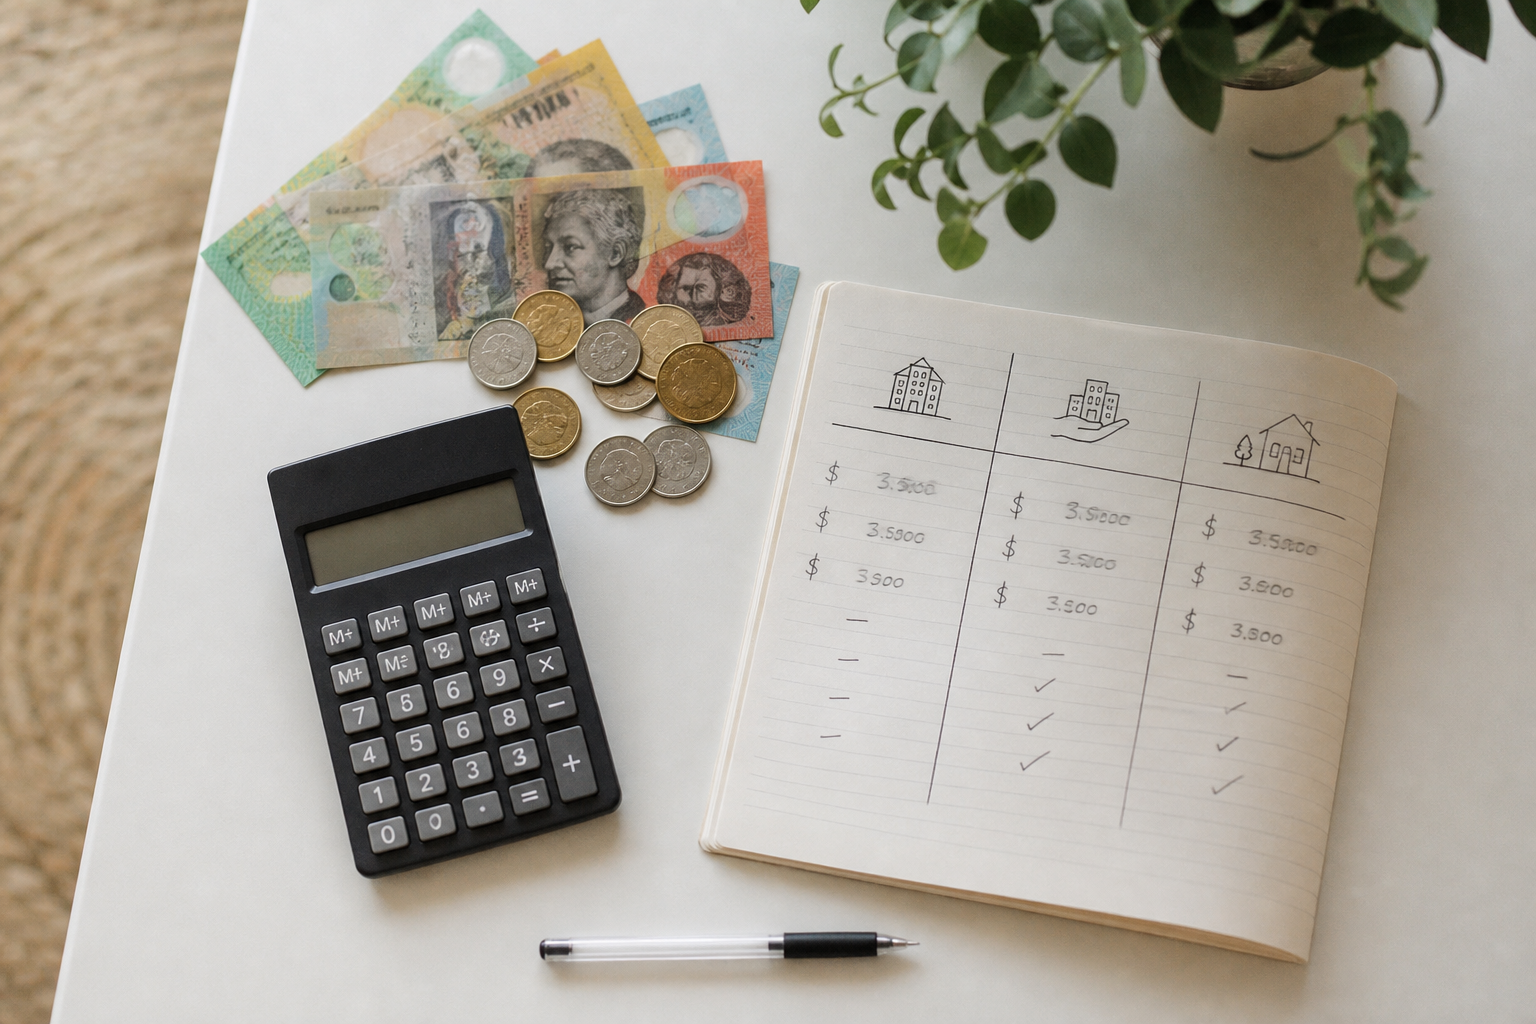
Step 1: Run a simple numbers test on each option
Before you get into lifestyle questions, test each option with the same numbers:
-
Total monthly housing cost now
Rent or board + any existing loan repayments + utilities you pay. -
Expected cost at settlement
New loan repayments stress‑tested at 3% above current rates (APRA buffer), plus strata, insurance and ongoing bills. -
Cash buffer
Savings/offset after moving, minus moving costs, bond, furniture and any rent overlap. -
Stability of income
Self‑employed? Assume a softer year and be conservative.
A good target, especially if you’ll end up with a mortgage, is:
- Total housing payments (rent + loans) under 30–35% of after‑tax income when stress‑tested at that 3% higher rate (see also /insights/interest-only-vs-principal-and-interest-high-income-investors).
- At least three months of future home repayments in cash or offset at settlement, ideally six.
Quick worked example
- Household after‑tax income: $10,000/month.
- Future off‑the‑plan loan (P&I) at stressed rate: $4,000/month.
- Target: keep current housing + future loan under about $3,000–$3,500/month now, and hold at least $12,000 in buffer for settlement.
Use this as a reference when you compare the three paths below.
Option 1: Keep renting – maximum flexibility
For many buyers, especially first‑timers, staying a renter is the cleanest play while you wait.
Pros
- Flexibility on delays. You can negotiate extensions or go month‑to‑month. We cover this more in /insights/align-lease-expiry-off-the-plan-handover-avoid-double-housing-costs.
- Clear cashflow. One rent payment, known utilities, no extra investment loan.
- Easier to stay ‘bank ready’. Simpler to show stable expenses when your lender reassesses you before settlement.
Cons
- You’re not building extra equity (besides the off‑the‑plan deposit and any extra savings).
- You carry the risk of double housing costs if the lease doesn’t line up with handover.
Best for you if:
- Your numbers are already tight at settlement.
- You value certainty and don’t want to juggle an extra property.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Is rentvesting a good idea while I’m waiting for my off-the-plan place?▾
How big should my cash buffer be before off-the-plan settlement?▾
What if my lease ends before my off-the-plan property is ready?▾
Request a strategy call
Confidential consultation with a triple-qualified advisor — commercial, SMSF, equipment and development finance.