
Article
Rent in the East, Buy Slightly West: A Smart Rentvesting Plan
How to keep living in Sydney’s Eastern Suburbs while buying a solid investment slightly west, with clear numbers, risks and a one‑week action plan.
Key Takeaway
Rentvesting in Sydney’s Eastern Suburbs means continuing to rent locally while buying a more affordable investment slightly west, using your borrowing power where it stretches further. With Woollahra median rents around $695 a week in 2021, many households can redirect savings into an investment mortgage instead. This guide outlines who rentvesting suits, example numbers, risk checks and a one‑week action plan so buyers can decide if renting in the east and buying west is a workable strategy now.
Watch the short answer
Can I get a home or business loan with a 12‑month-old business?
Running a new business and looking at finance? This video outlines options with only 12 months trading.
Read the transcript
Started a wildly successful business 12 months ago? The bank still thinks you're a startup risk. The standard institutional rule is that you need 2 full years of ABN history to get a mortgage, but if your cash flow is booming right now, you shouldn't have to wait another 12 months to buy a house. At Local Knowledge Finance, we have access to specialist alt doc lenders who will approve your loan with just 6 to 12 months of ABN registration and clean bank statements. Your success shouldn't be penalised by arbitrary timelines. DM me the word 'BUSINESS' to bypass the 2-year rule.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Tailored Loans Sydney
How to keep living in Sydney’s Eastern Suburbs while buying a solid investment slightly west, with clear numbers, risks and a one‑week action plan.
Read the full guide on tailoredloans.sydneyRentvesting in the Eastern Suburbs means you keep renting where you love living (Bondi, Bronte, Paddington), but you buy an investment in a cheaper, still‑solid area slightly west. You use your borrowing power where it goes further, while your tenant and tax deductions help service the debt.
Done well, this can be a bridge to your eventual Eastern Suburbs home rather than “renting forever”.
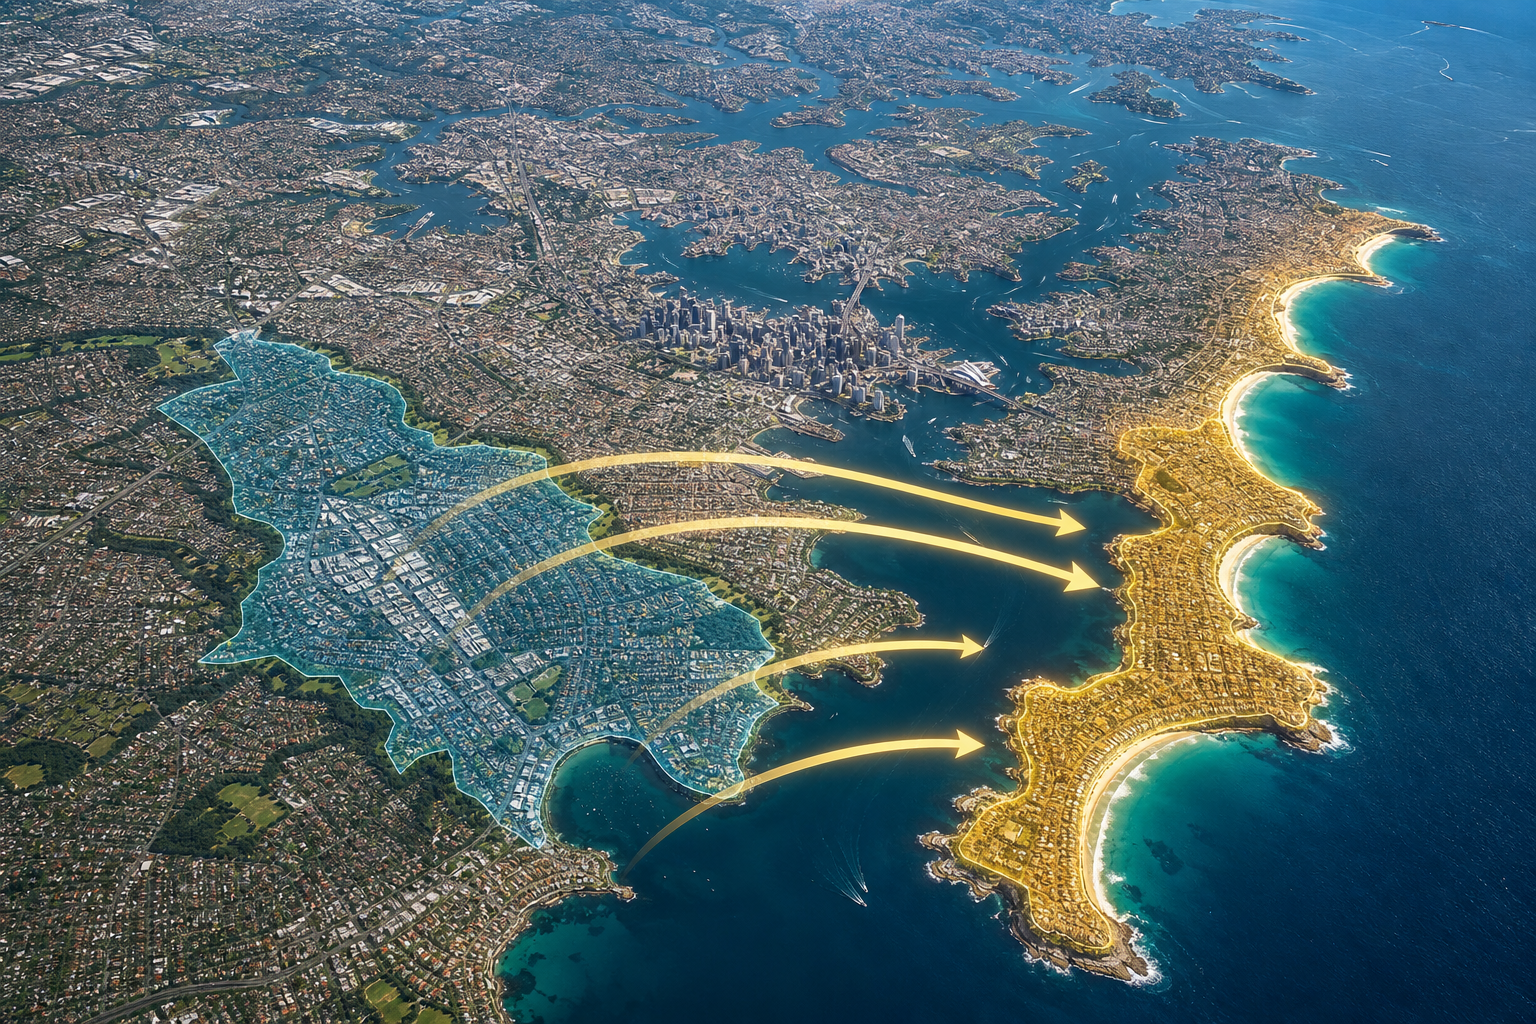
How the rentvesting numbers roughly stack up
Let’s keep it simple and indicative only.
Scenario A – Live and buy in the East
• Buy a $1.8m 2‑bed in Randwick.
• 20% deposit ($360k) plus stamp duty/fees ($90k).$2,030/week).
• Loan: $1.44m, 30 years, say 6.2% P&I (illustrative only).
• Repayments: ≈ $8,800 per month (
Scenario B – Rent in the East, buy slightly west
• Rent in Randwick/Bondi border: say $1,100/week for a decent 2‑bed (Woollahra’s 2021 median rent was $695/week, so this is realistic for a larger place).
• Buy a $950k townhouse in an Inner West / Bayside pocket (e.g. Arncliffe, Tempe, Dulwich Hill fringe).
• 15% deposit ($142,500) plus costs (~$50k).
• Loan: $807,500 at same rate/term.$1,130/week).
• Repayments: ≈ $4,900/month (
• Rent received from tenant: say $800/week.
• Net property cost before tax: $1,130 − $800 = ~$330/week.
Total weekly housing cost in Scenario B:
• Your rent $1,100 + $330 net holding cost ≈ $1,430/week.
That’s around $600/week less than owning in the East in this example, while you’re still building equity through the western property.
Your exact numbers will vary, but the pattern often holds: own slightly west + rent in the East can be cheaper and more flexible than stretching to own in the East straight away. (See also the worked numbers in [/insights/renting-nearby-vs-buying-bronte-2026-numbers].)
Who rentvesting suits (and who it doesn’t)
Rentvesting generally works best if:
- You value lifestyle or school zones in the East now, but can’t safely afford to buy there yet.
- You have a modest deposit (5–15%) and don’t want to wait 5+ years while prices run away.
- Your career or business location is central (CBD, North Sydney, airport, hospitals) and you want an easy commute.
- You’re comfortable being a landlord and accepting tenant, vacancy and repair risks.
It’s less suitable if:
- You strongly value security of tenure and hate the idea of a landlord notice ending your lease.
- Your income is volatile and you don’t yet have a 3–6 month buffer across home + investment costs.
- You’re not prepared to hold for at least 7–10 years (especially once you include stamp duty and selling costs – see the 7–10 year break‑even discussion in [/insights/renting-nearby-vs-buying-bronte-2026-numbers]).
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Is rentvesting a good idea in Sydney’s Eastern Suburbs?▾
How much deposit do I need to rentvest near the Eastern Suburbs?▾
Can I claim tax deductions on a rentvesting property?▾
Request a strategy call
Confidential consultation with a triple-qualified advisor — commercial, SMSF, equipment and development finance.