Article
How R2, R3 and R4 Zoning Really Drive Value in Sydney’s East
Understand how R2, R3 and R4 zoning in Sydney’s Eastern Suburbs affects bank valuations, renovation upside and development risk, so you can act confidently this week.
Key Takeaway
R2, R3 and R4 zoning in Sydney’s Eastern Suburbs change a property’s value because they define dwelling density and development intensity, and valuers price land off realistic “highest and best use.” For example, an R3 block near transport can trade 10–30% above similar R2 land due to townhouse or unit potential. Buyers and owners should cross‑check zoning, FSR and height limits, then align purchase price and loan structure to what can actually be built, not just what is theoretically allowed.
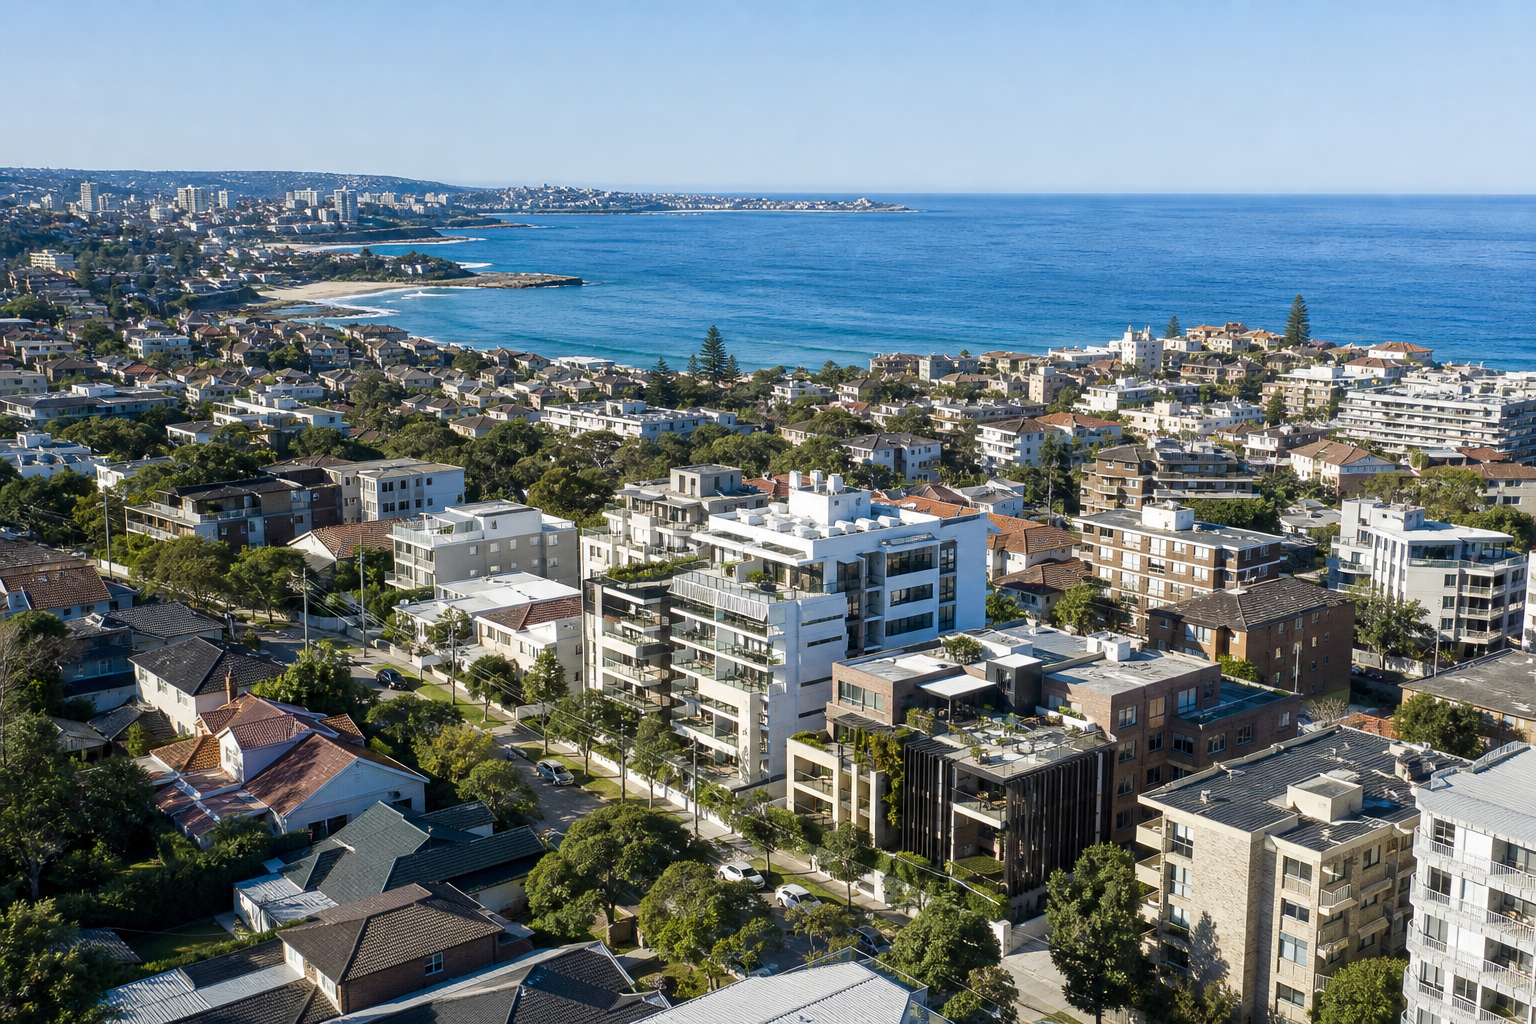
If you’re buying or refinancing in Sydney’s East, R2, R3 and R4 zoning matter because valuers use them to judge “highest and best use” and land value. In practice, an R3 block with realistic townhouse potential can be worth 10–30% more than a similar R2 block, while an R4 site with tight controls may be worth less than agents promise if the numbers don’t stack up.
This guide shows you how valuers think about zoning in the Eastern Suburbs so you can decide – this week – whether a site is fairly priced, over‑hyped or a quiet opportunity.
1. Zoning basics in Sydney’s East – what really changes value
1.1 Quick definitions
In most Eastern Suburbs LEPs (e.g. Woollahra, Waverley, Randwick):
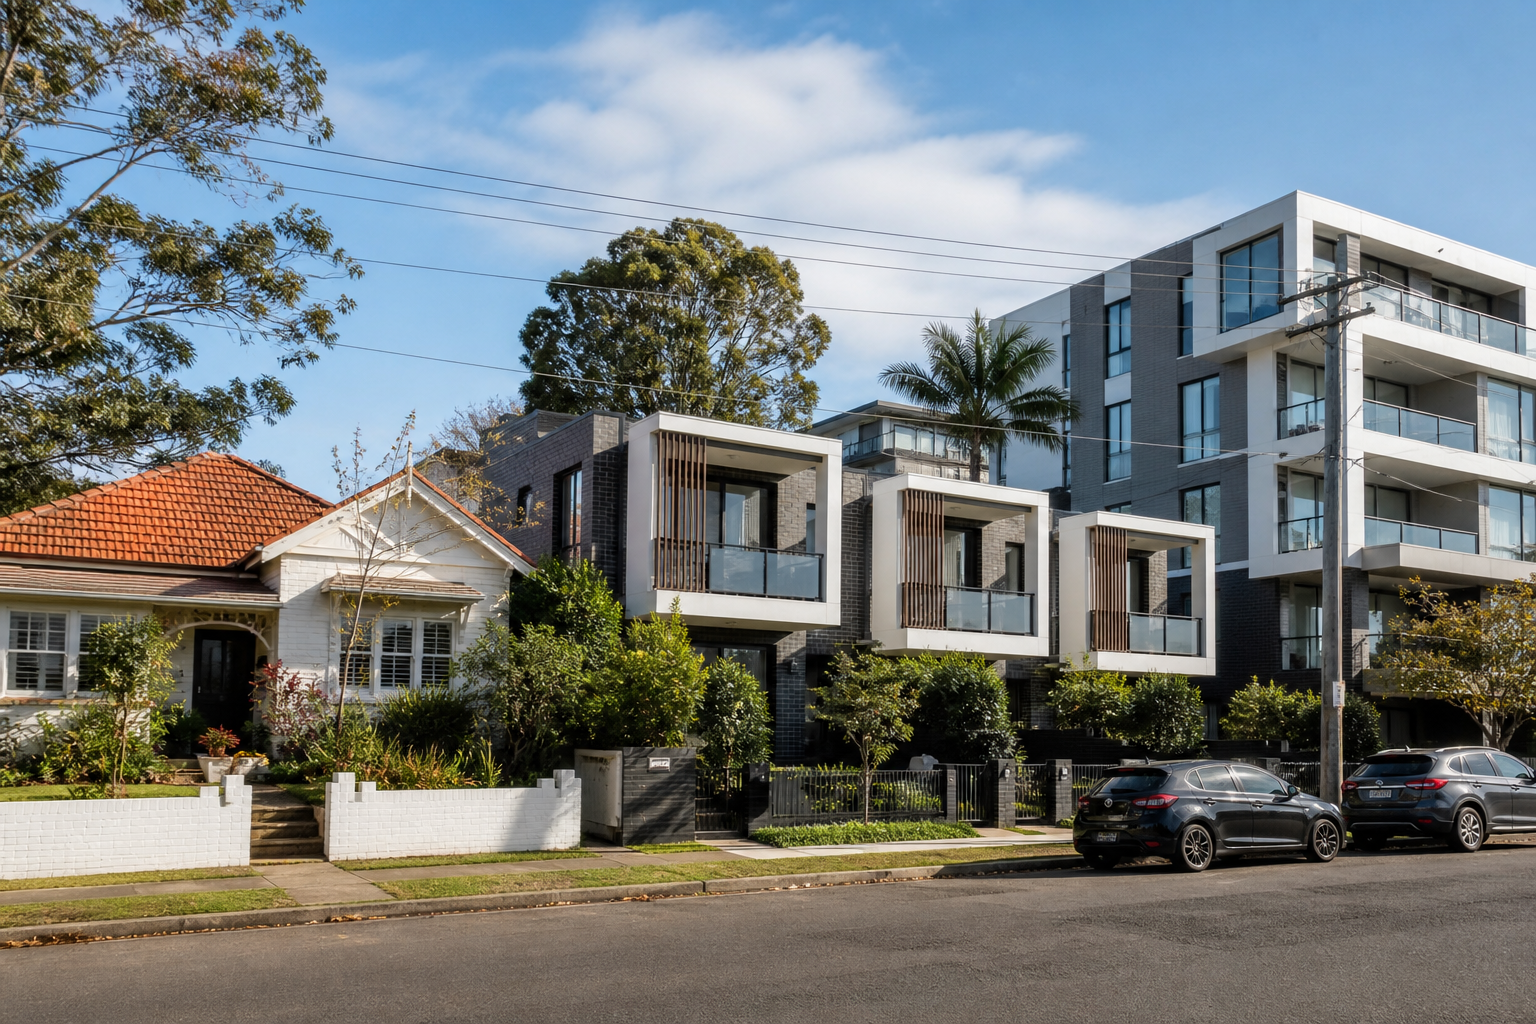
- R2 – Low Density Residential: typically detached houses, some dual occupancies and secondary dwellings (granny flats). Limited density.
- R3 – Medium Density Residential: townhouses, terraces, small unit blocks depending on FSR and height.
- R4 – High Density Residential: apartments, often higher FSR and height, usually close to transport and centres.
Zoning alone doesn’t set your value. Valuers overlay zoning with:
- Floor space ratio (FSR) – how much gross floor area you can build.
- Height limits – how many storeys are realistic.
- Site constraints – slope, shape, easements, trees, access, overshadowing.
- Market depth – is there real buyer demand for what you could build?
If you haven’t already, it’s worth pairing this with a street‑level view of how lenders see each pocket: see Finding Real Value in Sydney’s Eastern Suburbs: A Lender’s Street‑Level View.
1.2 How valuers translate zoning into a number
When a bank sends a valuer, they typically:
- Confirm zoning, FSR and height in the LEP.
- Identify the site’s highest and best use that is physically possible, legally permissible and financially feasible.
- Compare to recent sales of similar zoned land with similar development potential.
- Adjust for improvements (house condition, units on site) only where the market actually pays for them.
That’s why two similar houses can get very different vals if one sits on true R3 townhouse land and the other on constrained R2. For real examples of how this plays out in valuations, see Why Two Eastern Suburbs Properties Value So Differently (Real Cases).
2. R2 vs R3 vs R4 in the Eastern Suburbs – side‑by‑side
2.1 Typical patterns (illustrative only)
Zoning controls vary by council, but this comparison table captures common Eastern Suburbs patterns.
| Feature | R2 Low Density | R3 Medium Density | R4 High Density |
|---|---|---|---|
| Typical dwelling types | Houses, duplex, granny flat | Townhouses, small walk‑ups, terraces | Unit blocks, mixed‑use in centres |
| Indicative FSR range* | 0.5:1 – 0.7:1 | 0.7:1 – 1.2:1 | 1.2:1 – 2.5:1+ |
| Height limit (common range)* | 8.5–9.5m (2–3 storeys) | 9.5–12m (3–4 storeys) | 12–21m+ (4–7+ storeys) |
| Typical buyer competition | Owner‑occupiers | Small developers + owner‑occupiers | Developers, investors, some owner‑occupiers |
| Bank risk view | Generally lower density, predictable | Strong but more cyclical | More cyclical; closer scrutiny |
*Ranges are indicative only – always check the specific LEP and DCP.
The key: R3 and R4 land is valued as a development input, not just a home. If a feasible townhouse or unit scheme works on paper, land value jumps. If it doesn’t, the premium shrinks.
2.2 Worked example – zoning uplift in practice
Assume two 500 m² blocks in an inner‑east fringe location:
- Block A: R2, FSR 0.6:1, height 9.5m.
- Block B: R3, FSR 1.0:1, height 12m.
Rough development math (very simplified):
- R2 Block A: 0.6 × 500 = 300 m² allowable floor area. Realistic outcome: single dwelling + granny flat.
- R3 Block B: 1.0 × 500 = 500 m² allowable floor area. Realistic outcome: 3–4 townhouses.
If recent sales show:
- Renovated R2 houses on similar land: $4.0m.
- New 3–4 bed townhouses selling around $2.2m each.
A 4‑townhouse scheme with end values around $8.8m (4 × $2.2m), less build/soft costs and developer margin, may support a land value of, say, $4.5m–$5.0m for Block B.
The bank valuer will look at actual R3 land sales, not just this feasibility, but the principle holds: proper R3 has a structural edge over R2 if the site actually works.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
What is the main difference between R2, R3 and R4 zoning?▾
Does R3 zoning always mean my land is worth more than R2?▾
How do bank valuers treat speculative rezoning potential?▾
Can zoning changes affect my borrowing power when refinancing?▾
How do I quickly check the zoning and FSR of a property?▾
Request a strategy call
Confidential consultation with a triple-qualified advisor — commercial, SMSF, equipment and development finance.