
Article
Getting a Home Loan When You Owe the ATO: What Really Matters
You can often get a home loan even if you owe the ATO, but only when the debt is disclosed, under control and your cash flow still passes lender stress tests. This guide shows small‑business owners the real rules, what to fix first and when to apply.
Key Takeaway
Australian small‑business owners can often still get a home loan with ATO debt if the tax is fully disclosed, on a formal payment plan, and post‑tax cash flow comfortably passes lender stress tests with a 3% interest rate buffer. Lenders weigh the size and age of ATO arrears, lodgement history, and business stability more than the mere existence of debt. The key actionable step is to move from ‘ignored’ to ‘managed’ ATO debt before lodging a mortgage application.
Watch the short answer
How ABN age can affect your chances with the banks
Find out why many lenders care how long your ABN has been active before they lend.
Read the transcript
Most banks have a rigid rule: if your ABN hasn't been active for two full years, you can't get a home loan. But if your trade business has been booming for 12 months, why should your family wait to buy a house? We have direct access to alternative doc lenders who accept 6 to 12 months of active trading backed by clean business bank deposits. Stop waiting for arbitrary timelines. DM me 'GROWTH' to look at your options.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Tailored Loans Sydney
You can often get a home loan even if you owe the ATO, but only when the debt is disclosed, under control and your cash flow still passes lender stress tests. This guide shows small‑business owners the real rules, what to fix first and when to apply.
Read the full guide on tailoredloans.sydneyYou can sometimes get a home loan while you owe the ATO, but only if the debt is fully disclosed, on a realistic payment plan, and your post‑tax cash flow still passes lender stress tests. If the debt is large, ignored, or your BAS and returns are overdue, most mainstream banks will either decline you or slash your borrowing power.
How lenders really treat ATO debt
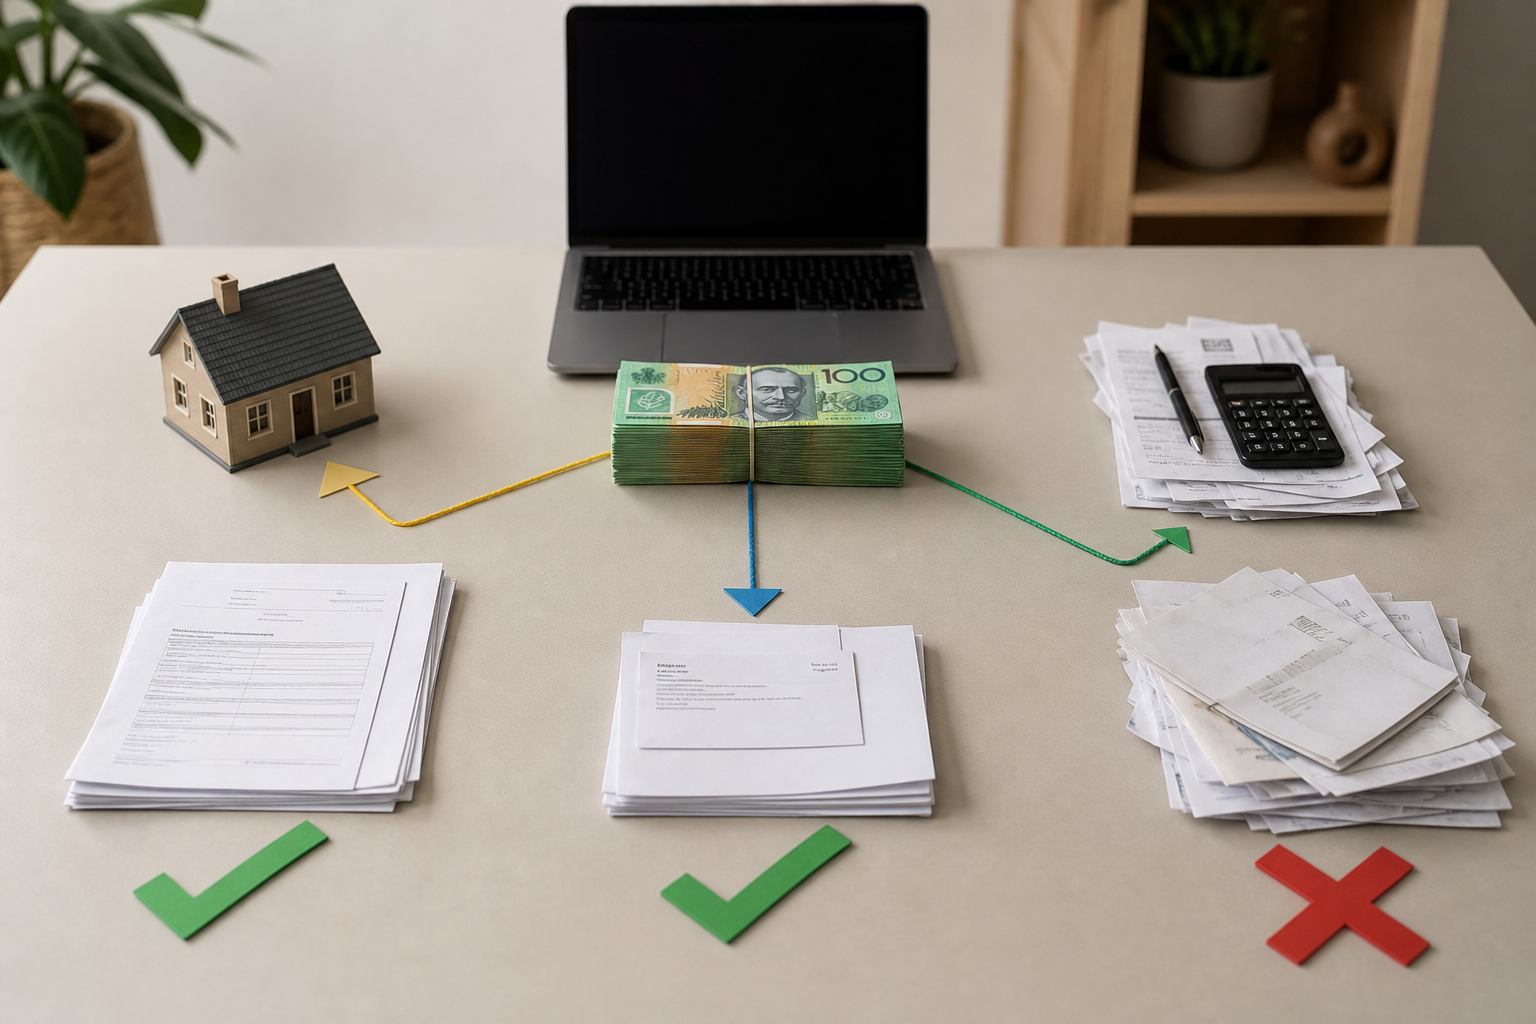
For small‑business owners, lenders don’t just ask “Do you owe tax?” — they ask three questions:
- Is everything lodged? (tax, BAS, PAYG)
- Is the ATO debt managed? (formal plan vs hoping it goes away)
- Can you safely afford mortgage + ATO + business costs at buffered rates?
ATO debt is usually treated as priority debt.
If you get into trouble, the ATO tends to get paid before the bank.
That’s why undisclosed or messy tax positions are a red flag.
For more detail on how banks frame this risk, see /insights/ato-debt-payment-plans-home-loans-what-lenders-think.
What usually kills an application
Lenders get very nervous when they see:
- Unlodged returns or BAS for the last 1–2 years.
- ATO payment plans that don’t actually match your cash flow (you’re already missing instalments).
- Garnishee notices on bank statements.
- Evidence you’re using home loan redraw as recurring working capital for BAS, wages or GST — that effectively turns your mortgage into an overdraft and concentrates business risk on the family home.
Any of these can push you from a prime lender into specialist territory, with higher rates and lower borrowing limits.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Can I get a home loan if I’m on an ATO payment plan?▾
Do I have to pay out my ATO debt before applying for a mortgage?▾
How much ATO debt is too much for a home loan?▾
Request a strategy call
Confidential consultation with a triple-qualified advisor — commercial, SMSF, equipment and development finance.