
Article
Do Harbour Views Really Boost How Much the Bank Will Lend?
Harbour glimpses and full views price very differently, but banks recognise the premium unevenly. Here’s how valuers actually treat views, what that does to your borrowing limit and LVR, and how to structure your finance this week so you don’t overbid on a view the bank won’t really pay for.
Key Takeaway
Banks lend against bank valuation, not agent hype, so harbour glimpses often get little or no premium while genuine, protected harbour views in Sydney’s east can add 5–20% to a valuation if recent comparable sales support it. This directly changes borrowing power and LVR, especially around 80% and 90% thresholds. Buyers should line up a lender-aligned valuation, stress-test gearing, and plan auction limits around the lower of price expectations and bank valuation.
Watch the short answer
How ABN age can affect your chances with the banks
Find out why many lenders care how long your ABN has been active before they lend.
Read the transcript
Most banks have a rigid rule: if your ABN hasn't been active for two full years, you can't get a home loan. But if your trade business has been booming for 12 months, why should your family wait to buy a house? We have direct access to alternative doc lenders who accept 6 to 12 months of active trading backed by clean business bank deposits. Stop waiting for arbitrary timelines. DM me 'GROWTH' to look at your options.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Tailored Loans Sydney
Harbour glimpses and full views price very differently, but banks recognise the premium unevenly. Here’s how valuers actually treat views, what that does to your borrowing limit and LVR, and how to structure your finance this week so you don’t overbid on a view the bank won’t really pay for.
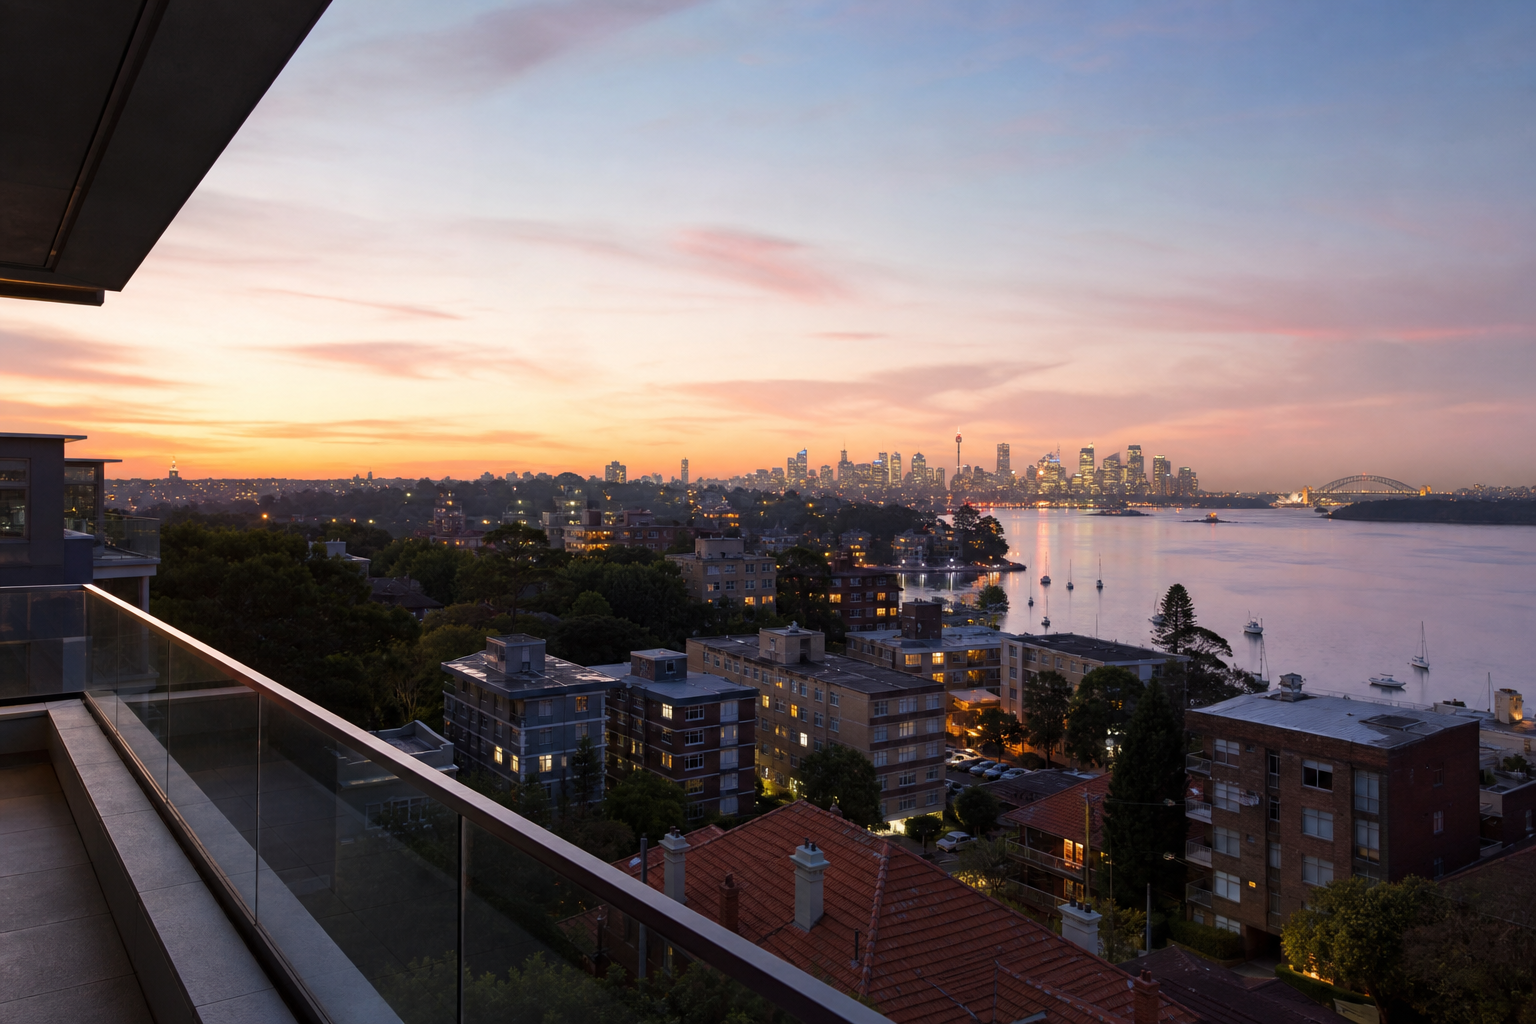
Read the full guide on tailoredloans.sydneyBanks care far less about your romantic harbour view than about recent, provable sales. A genuine, protected harbour view in Double Bay or Bellevue Hill might lift a bank valuation by 5–20% if recent comparables back it, while a simple ‘harbour glimpse’ often adds little or nothing. That gap can mean a $200k+ difference in what you can safely borrow at standard LVRs.
How valuers actually price views for your loan
Bank valuers don’t price emotion. They benchmark your apartment or house against recent local sales, then adjust up or down.
For views, they usually look at:
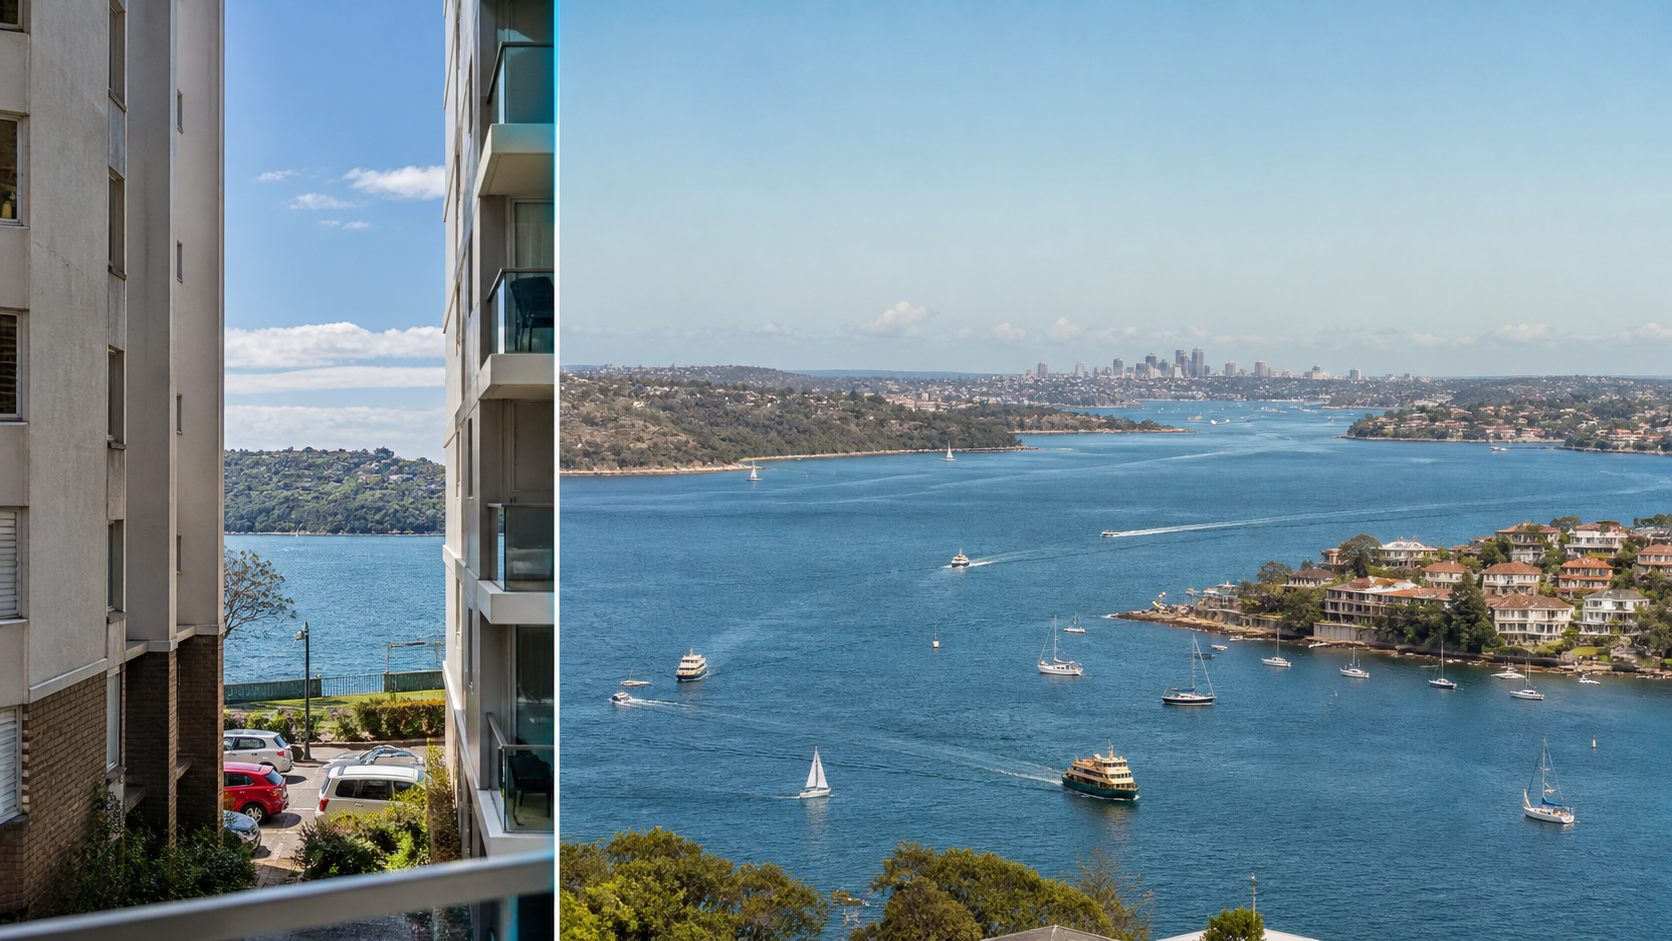
- Type of view – uninterrupted, partial, or a tiny glimpse from the balcony.
- Depth and width – full sweep of harbour vs a narrow shaft between buildings.
- Permanence – risk of future obstruction from nearby development.
- Level and aspect – how high, which direction, and how much daylight.
- Suburb and micro‑pocket – Double Bay foreshore isn’t treated the same as a busy road further back.
A working rule of thumb many valuers use in Sydney’s east:
- True, protected harbour view: often +5–20% vs a similar non‑view property.
- Harbour glimpse/oblique partial: sometimes 0–5%, and in softer markets, 0%.
If you want more detail on how sales are chosen and adjusted, see /insights/how-local-valuers-benchmark-eastern-suburbs-sales-loan-impact.
Example: same block, different view
- Non‑view 2‑bed in the block sold and valued at $2.0m.
- Your full‑view 2‑bed is genuinely superior on aspect and depth.
- Valuer might land at $2.2m–$2.3m if recent full‑view sales support it.
- But if the only recent sale is the non‑view one, the valuer may stay tight at $2.05m–$2.1m.
That band is what your loan is built on, not the agent’s $2.4m ‘price guide’.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Do harbour glimpses really increase how much I can borrow?▾
Why is my bank valuation lower than the agent’s price guide for a view apartment?▾
Should I change banks to get a better valuation for my view property?▾
Request a strategy call
Confidential consultation with a triple-qualified advisor — commercial, SMSF, equipment and development finance.