Article
Where To Hold Your Business Premises: SMSF, Property Company or Trust?
A practical guide for Australian business owners weighing up whether to hold their business premises in an SMSF, a property company or a trust – with focus on tax, risk, borrowing and exit planning.
Key Takeaway
This article explains whether Australian business premises are best owned in an SMSF, a property company or a trust, focusing on tax, asset protection, lending and exit planning. It outlines that most lenders assess all entity debts together, so SMSF or company loans can still reduce personal borrowing capacity. It concludes that business owners should model 5–10 years of combined cashflow and choose a structure that matches retirement timing and business sale plans before committing.
Owning your own business premises can be a smart move, but where you park the title – your SMSF, a property company or a trust – will ripple through your tax bill, asset protection, borrowing power and retirement plan for decades.
For most Australian business owners, there is no single “best” structure. An SMSF can deliver strong tax outcomes in retirement, a property company can be simple and bank‑friendly, and a discretionary trust can give flexibility and asset protection – but you rarely get all three at once. The right choice comes from lining up structure, lending and exit planning, not just chasing tax.
Below is a decision‑grade guide you can use this week to narrow your options, then sit down with your accountant, lawyer and broker to sanity‑check the numbers.
1. Start with your real goals, not the structure labels
Before comparing SMSF vs company vs trust, get clear on what you’re actually trying to achieve in the next 5–10 years.
1.1 The five questions that usually decide the structure
Most business‑premises structures come back to these questions:
-
How close are you to retirement?
• Within 10 years: SMSF often becomes more attractive.
• 10–20+ years away: flexibility and borrowing power often matter more. -
How risky is your trading business?
• High risk (construction, hospitality, advisory with PI exposure): keeping premises away from the trading entity is usually critical.
• Lower risk (stable professional services, long‑term contracts): you may trade off some protection for simplicity. -
Do you expect to sell the business, the property, both – or neither?
Your exit sequence (and whether you want to keep the property as a retirement asset) heavily influences the ideal owner. -
What’s your current borrowing capacity – personal, business and SMSF?
Once SMSF, company or trust borrowing is involved, most lenders assess everything as one ecosystem, so an extra loan in any entity can still reduce your home‑loan capacity (knowledge fact 2). -
Are you comfortable locking money away in super?
Contributions into an SMSF are usually trapped until preservation age. That can be great for discipline – or a problem if you’re under‑funded outside super.
1.2 Big picture: separate business risk from long‑term assets
Whatever you choose, one principle is almost universal: keep trading risk away from your core assets.
If your premises share loans, guarantees and securities with the trading company and your home, a bad year can turn into a multi‑property fire sale. Clean separation of ownership, loans and cash buffers is the backbone of keeping your business and property safe from each other’s risks (see /insights/protecting-business-from-property-risks-and-vice-versa).
2. SMSF owning the business premises: when it fits, when it doesn’t
Putting your business premises in your SMSF is popular for doctors, tradies and professional practices. The SMSF buys the property and your business pays commercial rent to your super fund under a related‑party lease.
2.1 Why people like SMSFs for business premises
Key potential advantages:
- Concessionally taxed rent:
• SMSF in accumulation: 15% tax on net rent and capital gains (10% if property held >12 months).
• In pension phase: 0% tax on income and (within limits) capital gains. - Asset protection: The property sits inside super, generally protected from creditors if you’re sued or the business fails (subject to clawback rules for deliberate transfers to defeat creditors).
- Forced retirement savings: Your business rent boosts your retirement asset instead of a third‑party landlord.
For a deeper dive on how SMSF property works more generally, see /insights/residential-vs-commercial-smsf-property-updated-tax-settings.
2.2 The trade‑offs and traps
Common drawbacks:
- Borrowing limits and higher costs:
• SMSF loans usually have lower maximum LVRs (often capped around 65–70% for commercial) and stricter serviceability.
• Setup (bare trust, legal advice) and ongoing audit costs are higher. - Reduced personal borrowing capacity: Even if the SMSF loan is “ring‑fenced”, most lenders still factor it into your overall risk and cashflow profile, which can reduce how much you can borrow for your home or other business needs (knowledge fact 2).
- Liquidity and contribution caps:
• Your ability to support a vacancy, repairs or rate rises is capped by contribution limits and your existing super balance.
• You generally can’t tip in big lump sums after a bad year without bumping against caps or age limits. - Inflexible exit: Selling or transferring SMSF property has tax and compliance friction. You can’t just draw equity out for personal use.
2.3 Worked example – SMSF vs company ownership
Assume:
- Property price: $1.5m
- Net rent from your business: $90,000 p.a. (6% yield)
- Interest rate: 7.0% p.a. (indicative only)
- Loan: 65% LVR in SMSF ($975k), 70% LVR in company ($1.05m)
- Other costs (repairs, land tax, etc.): $15,000 p.a.
SMSF owns property
- Interest: $68,250
- Net income before costs: $21,750
- After other costs: $6,750
- Tax at 15%: $1,013
- Net after tax: ~$5,737
Property company (at 25% small business company tax rate)
- Interest: $73,500
- Net income before costs: $16,500
- After other costs: $1,500
- Tax at 25%: $375
- Net after tax: $1,125
In this simplified scenario, the SMSF is ahead on an annual tax basis – but:
- The SMSF had to contribute more equity up front.
- Borrowing that same equity into your home or business may have produced different after‑tax outcomes.
- SMSF borrowing might limit your capacity for a new home or investment property.
The right choice is about the whole ecosystem, not just one entity’s tax rate.
2.4 When SMSF ownership tends to work best
SMSF ownership of business premises usually works best when:
- You are within 5–15 years of retirement and want a stable, long‑term SMSF asset.
- You already have a meaningful SMSF balance (or can build one quickly) so the fund isn’t over‑concentrated in a single property.
- You can service the SMSF loan from rent plus super contributions, even if business profits dip.
- You are comfortable locking capital inside super and dealing with more compliance.
If you’re 40 with a young business, big home loan and thin super, aggressively gearing your SMSF into the premises can be a red flag.
3. Property company: clean, simple and bank‑friendly
A dedicated property company (separate from the trading company) is often the simplest structure for lenders and for future buyers.
3.1 How it works
- A new company (PropCo) is set up to buy the property.
- Your trading company or trust (TradeCo) signs a commercial lease with PropCo.
- PropCo may be owned by you personally, a family trust, or a combination.
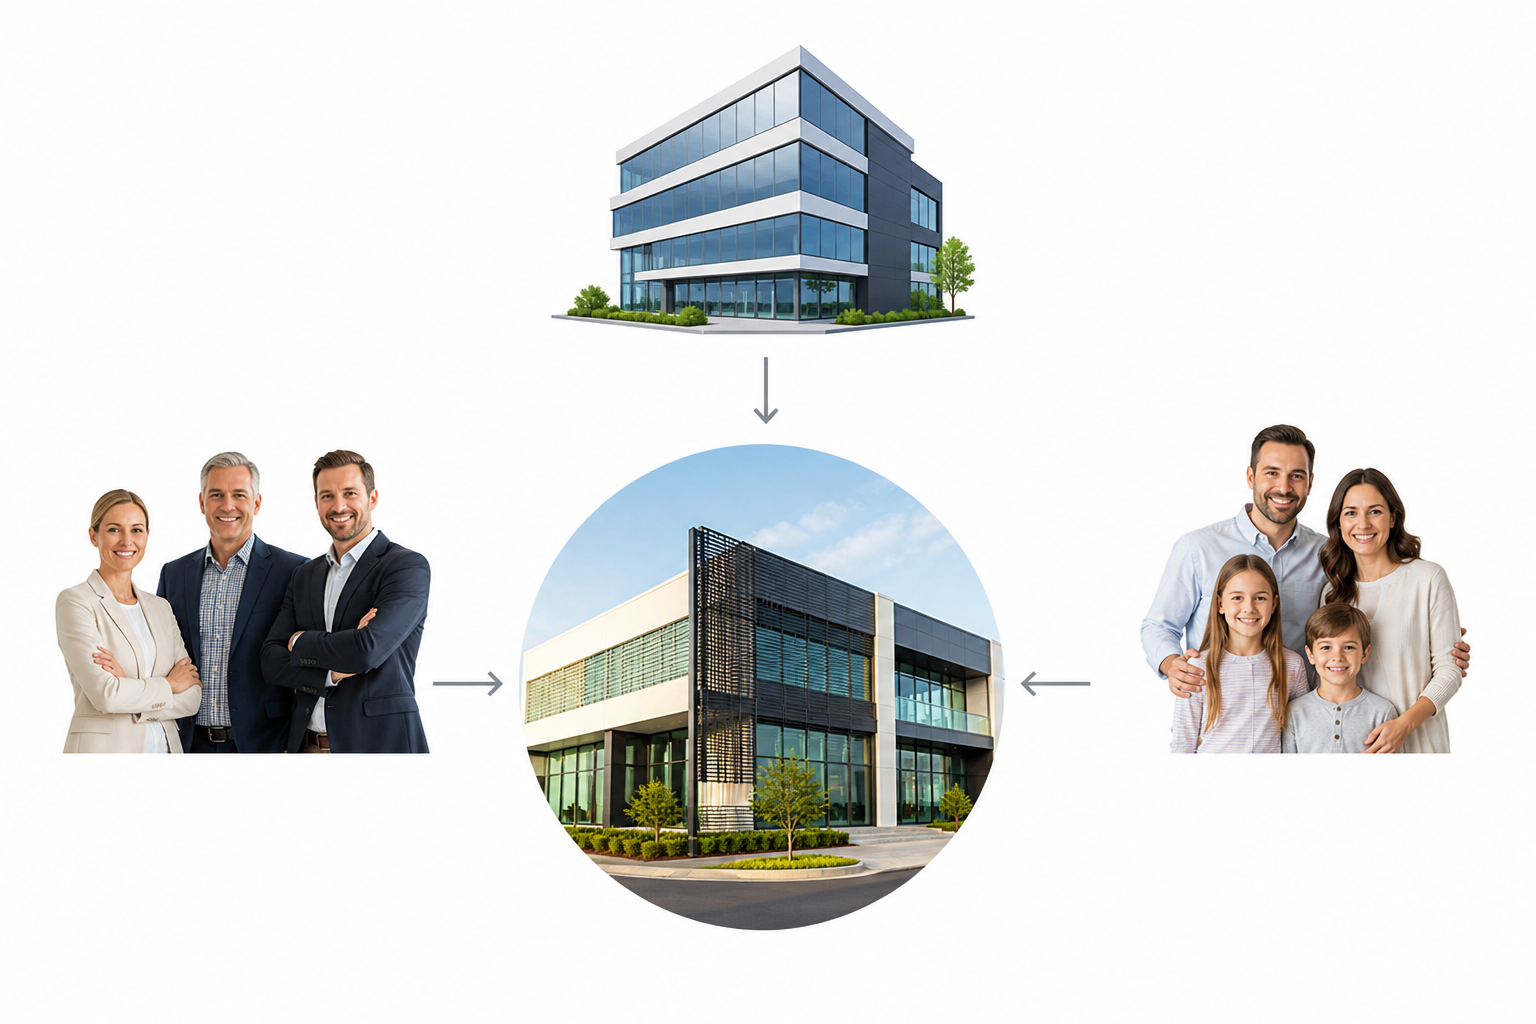
Your group structure might look like:
You → Discretionary Trust → PropCo → Owns property
You → TradeCo → Runs the business and pays rent to PropCo
3.2 Advantages of a property company
- Clear separation of risk: If TradeCo fails, PropCo can keep the property and lease to someone else (subject to personal guarantees and cross‑collateralisation with the bank).
- Simple for banks: Lenders are used to stand‑alone commercial property companies. Financials are easier to read than layered trusts.
- Franking credits: PropCo pays company tax (typically 25% if base rate entity) and can frank dividends to shareholders. This can suit family groups on mixed marginal tax rates.
- Easier sale and succession: You can sell the business but keep the property as a retirement income asset, or vice versa.
3.3 Drawbacks and issues
- Less flexible than a discretionary trust: Company profits are taxed at the corporate rate; getting capital gains and land into other hands without extra tax can be tricky.
- Double tax risk on exit: If PropCo sells the property, profit is taxed in the company, then again if you want cash out as dividends (partially offset by franking credits).
- Division 7A and shareholder loans: Sloppy inter‑entity loans can trigger deemed dividends and extra tax.
3.4 Where property companies usually fit best
A property company often suits when:
- You want straightforward banking and a structure commercial lenders understand.
- You plan to build a small portfolio of commercial properties.
- You prefer the discipline of company tax and franking credits over trust distributions.
If you already have a well‑run family trust that owns other assets, you may instead have that trust own the property company shares to add flexibility.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA-certified brokers use, including 7 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Is it always better to hold business premises in my SMSF for tax reasons?▾
Can my trading company just buy the premises in its own name?▾
How does land tax on commercial property in NSW affect my choice?▾
Will a loan in my SMSF, property company or trust hurt my home-loan approval?▾
What happens if my business fails but the property is in another entity?▾
Who should help me decide between SMSF, company and trust ownership?▾
Request a strategy call
Confidential consultation with a triple-qualified advisor — commercial, SMSF, equipment and development finance.