
Article
Choosing Between Business Lines of Credit and Term Loans
Trying to pick between a business line of credit and a term loan? This quick guide compares flexibility, cost and tax treatment so you can choose the right structure for your cashflow and protect your home and borrowing power.
Key Takeaway
A business line of credit suits short-term, repeating cash gaps, while a term loan is better for one-off, longer-term business needs like fit-out or permanent stock, making purpose and term the key decision drivers. In Australia, interest on both is generally tax-deductible where the borrowing is used to earn assessable business income, with clearer tracing on term loans. Owners should match facility type to cashflow, ring‑fence business debt from home loans, and review limits annually to protect borrowing power and the family home.
Watch the short answer
How ABN age can affect your chances with the banks
While you compare lines of credit and term loans, this video explains how your ABN age can shape your home and business lending options.
Read the transcript
Most banks have a rigid rule: if your ABN hasn't been active for two full years, you can't get a home loan. But if your trade business has been booming for 12 months, why should your family wait to buy a house? We have direct access to alternative doc lenders who accept 6 to 12 months of active trading backed by clean business bank deposits. Stop waiting for arbitrary timelines. DM me 'GROWTH' to look at your options.
General information only, not personal advice. Your situation is assessed before any recommendation.
A business line of credit is usually best for short-term, repeat cash gaps, while a term loan is better for one-off, longer-term needs like a fit-out, vehicle or permanent stock. The decision turns on three things: how often you’ll redraw, how long you’ll need the money, and how clean you want the tax and home-loan story to look.
Here’s how to choose, and what you can tweak this week.
Quick definitions: what each facility actually does
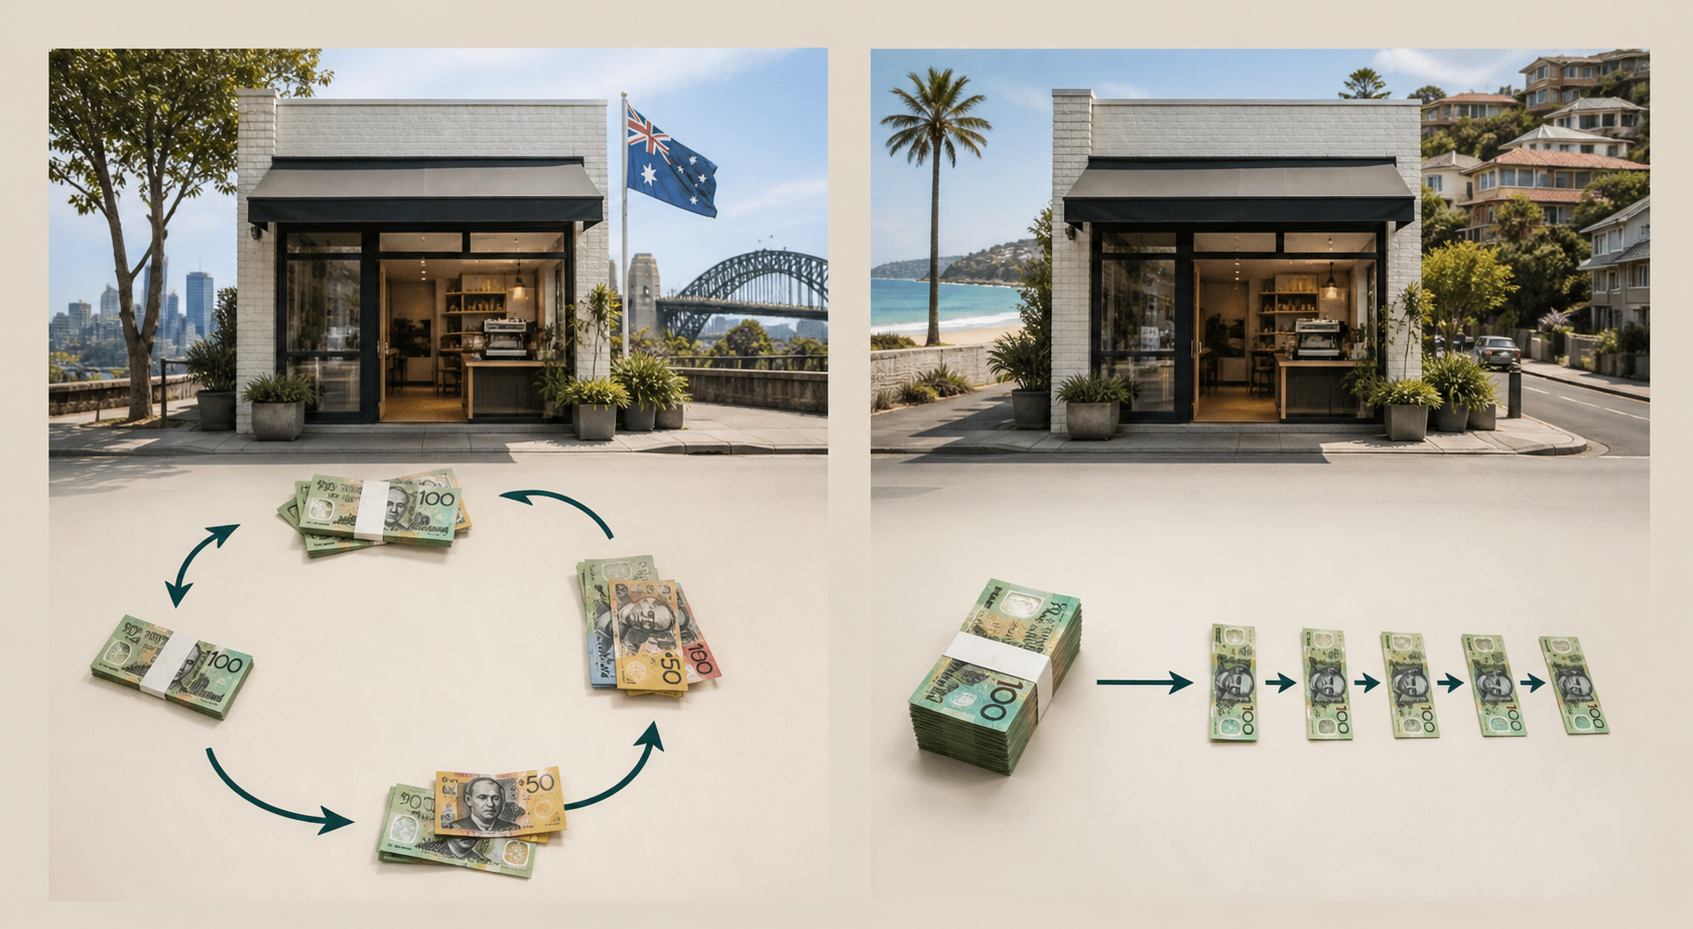
Business line of credit (LOC / overdraft)
- A revolving working capital facility with a limit (say $100k).
- You can draw up and down inside the limit without reapplying.
- Interest is only charged on the balance used, calculated daily.
- Often secured by property or a general business charge.
Business term loan
- Fixed amount advanced upfront (say $100k).
- Set term (e.g. 3–7 years) with scheduled principal and interest.
- You generally can’t redraw unless the product allows it.
- Often secured by specific assets or property.
For a bigger overview of working capital tools, see Working Capital Basics: Structures, Costs And Safe Limits For SMEs.
Flexibility: when a line of credit wins (and when it backfires)
Lines of credit are built for timing gaps, not long-term funding.
Best uses:
- Seasonal stock or project costs you recover in 30–120 days.
- BAS, PAYG and wages in slow months (if you clear it quickly).
- Jobs where you pay suppliers now and get paid at completion.
Risky uses:
- Funding fit-outs, vehicles or permanent team roles.
- Rolling unpaid ATO debt from one quarter into the next.
- Using your home loan redraw as the de facto overdraft (a major red flag for lenders and messy for tax).
Term loans are less flexible but force discipline:
- Predictable repayments.
- A clear end date.
- Harder to quietly let a short-term problem become a permanent one.
Rule of thumb: if you’ll pay it back within 12 months and might need it again, consider a LOC. If it’ll take years to repay, structure it as a term loan.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
Is interest on a business line of credit tax-deductible in Australia?▾
When should I use a term loan instead of a line of credit?▾
Does a business overdraft affect my home loan borrowing power?▾
Request a strategy call
Confidential consultation with a triple-qualified advisor — commercial, SMSF, equipment and development finance.