
Article
Turn One Loan Into a 15‑Year Property and Mortgage Plan
How to sit down with your broker this week and map a simple 10–15 year property and mortgage plan you can actually stick to, even as life and interest rates change.
Key Takeaway
Designing a 10–15 year property and mortgage plan means mapping 3–4 likely property moves, sequencing them around life events, and setting clear rules for debt, buffers and refinancing with your broker. With stamp duty pushing breakeven horizons towards 7–10 years on high-priced property and APRA’s 3% serviceability buffer tightening borrowing, long-term planning cuts risk and wasted costs. A practical first step is a two-hour strategy session to document goals, key moves and review dates.
Watch the short answer
How ABN age can affect your chances with the banks
As you map out a 10–15 year property and mortgage plan, this video explains how your ABN age can shape your home and business lending options.
Read the transcript
Most banks have a rigid rule: if your ABN hasn't been active for two full years, you can't get a home loan. But if your trade business has been booming for 12 months, why should your family wait to buy a house? We have direct access to alternative doc lenders who accept 6 to 12 months of active trading backed by clean business bank deposits. Stop waiting for arbitrary timelines. DM me 'GROWTH' to look at your options.
General information only, not personal advice. Your situation is assessed before any recommendation.
This topic is covered in full on Tailored Loans Sydney
How to sit down with your broker this week and map a simple 10–15 year property and mortgage plan you can actually stick to, even as life and interest rates change.
Read the full guide on tailoredloans.sydneyA 10–15 year property and mortgage plan is a simple written roadmap of 3–4 likely property moves, your target debt levels, and when you’ll refinance or de‑risk — all mapped with your broker around life events. It turns one loan conversation into a long-term strategy so every purchase, refinance and upgrade pushes you towards the same end point instead of random decisions.
Quick answer: In one 60–90 minute session, your broker can help you document (1) where you want to live in 10–15 years, (2) 3–4 likely transactions to get there, (3) rules for borrowing, buffers and equity use, and (4) a review schedule so the plan stays live.
Step 1: Start with your 10–15 year end point
Before talking lenders or rates, your broker should ask: “Where do you want to be living and how much debt are you happy to carry in 10–15 years?”
For many clients, the end point is:
- Own (or nearly own) a long-term home in a preferred suburb.
- Optional: 1–2 investments or a business premises.
- Manageable debt entering your 50s–60s, not maximum borrowing.
If you’re in Sydney’s East, that mirrors the approach in our Eastern Suburbs roadmaps for Dover Heights and Rose Bay [/insights/10-15-year-dover-heights-property-mortgage-plan] [/insights/10-15-year-rose-bay-family-property-mortgage-plan].
A quick worked example
Say you’re 38, combined income $280k, PPOR worth $1.7m with a $1.1m loan.
In 15 years (age ~53) you might target:
- Home: upgraded to ~$2.4m value, loan down to ~$900k.
- One investment unit: $1m value, $600k loan.
- Total debt: ~$1.5m on household income likely higher than today.
Everything in your plan should be checked against whether it makes this picture more or less likely.
Step 2: Map 3–4 key property moves
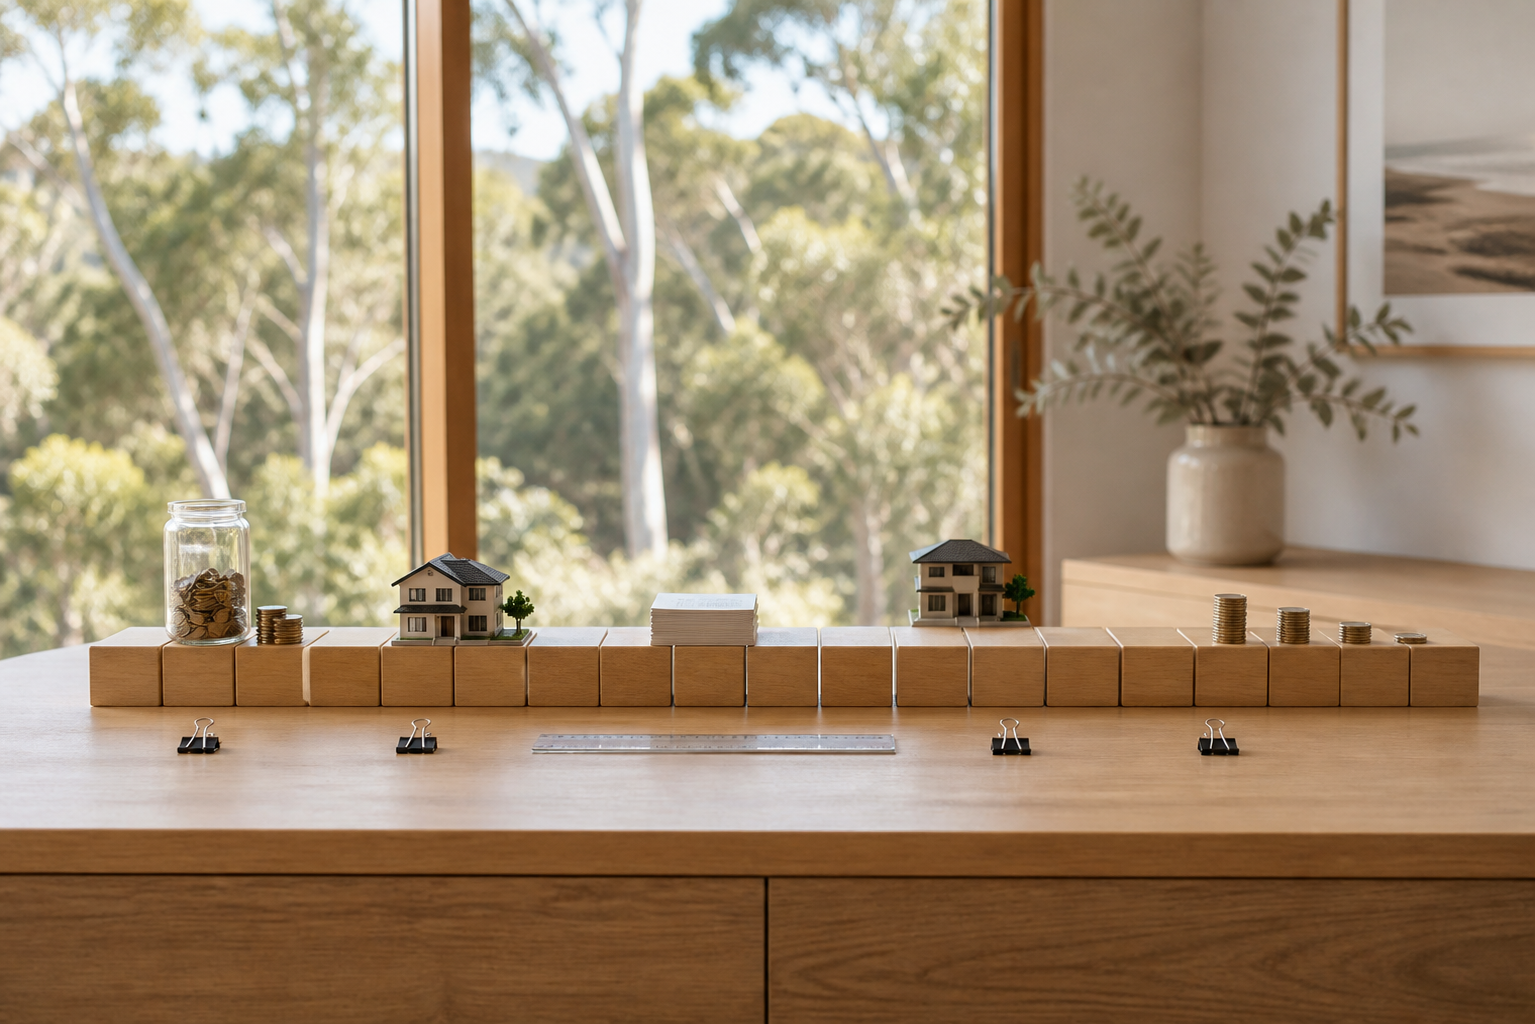
A practical plan does not guess every detail. It outlines the sequence of major moves:
- Move 1 (Years 0–3): e.g. refinance and tidy structure.
- Move 2 (Years 3–7): e.g. upgrade home or buy first investment.
- Move 3 (Years 7–12): e.g. convert old home to investment, buy business premises, or consolidate.
- Move 4 (Years 12–15): e.g. heavy debt reduction, sell underperformers.
Your broker’s job is to ensure each move is:
- Serviceable under APRA’s 3% buffer.
- Sensible given transaction costs (stamp duty often pushes breakeven to 7–10 years on high-priced property (src: /insights/renting-nearby-vs-buying-bronte-2026-numbers)).
- Flexible if interest rates or your income change.
The strategy continues below
You've seen the problem and the groundwork — now unlock the exact steps our CPA and Registered Tax Agent-led brokers use, including 4 more sections. Enter your email for instant, free full access.
Free access. No spam — unsubscribe anytime. Your details stay confidential.
Frequently asked questions
How often should I change my 10–15 year property plan?▾
Can I build a 10–15 year plan if I’m self-employed?▾
What if interest rates stay high for several years?▾
Request a strategy call
Confidential consultation with a triple-qualified advisor — commercial, SMSF, equipment and development finance.